Tuesday, 10 November 2026

The first rate rise in three years: what 4% means for buyers, sellers and remortgagers in Clapham, Battersea and Streatham

Well, it finally happened. After ten meetings sitting on its hands, the Bank of England has put rates up.

What did the Bank of England actually do?

On 5 November the Monetary Policy Committee voted 8-1 to raise Bank Rate by 0.25 percentage points, from 3.75% to 4%. The one dissenter, Catherine Mann, wanted to go further, to 4.25%. It's the first rise since August 2023.

Why did rates go up?

Energy. The Bank says the conflict in the Middle East has pushed energy prices up from an already high level. CPI inflation hit 3.5% in September and the Bank expects it to reach around 5% by the middle of next year.

Will there be more rises?

Governor Andrew Bailey told the BBC this shouldn't be seen as the first in an "inevitably long sequence of hikes", but "neither does it seem likely to be the last" unless the Iran war is resolved. So, not a straight answer. Truth of the matter is, nobody knows.

How much more will my mortgage cost?

Lenders moved before the Bank did. Moneyfacts says the average two-year fixed rate is now 5.97%, up from 4.83% at the start of 2026. On a £250,000 mortgage over 25 years, that's £169 a month more, or £2,028 a year, than a deal taken in January.

The 0.25% rise on its own adds around £37 a month on the same £250,000 loan, according to Moneyfacts. Tracker borrowers feel that first.

What does it mean for buyers in Clapham, Battersea and Streatham?

Bigger loans, bigger hit. A typical first-time buyer loan round here is about £400,000, which is a lot more than £250,000, so the monthly jump is bigger too. On that size of loan, the 0.25% rise alone is around £59 a month.

Lenders also test affordability at higher rates, so some buyers will find their budget has shrunk since the summer.

What does it mean for sellers?

Price for the buyer who exists today, not the one who existed in January. A buyer's mortgage offer sets the ceiling, and that ceiling has come down for many of them. Sellers Between the Commons or in Clapham Old Town with cash-rich or equity-rich buyers will feel it least.

What should I do if my fixed rate ends next year?

Moneyfacts suggests looking at a product transfer three to six months before your deal ends. Whatever you do, don't drift onto your lender's standard variable rate, which averages 7.13%. Take independent mortgage advice, of course.

My take

Let's face it, nobody enjoys a rate rise. But a quarter point isn't a crash. Bailey is hinting this is a nudge, not a sprint. The bigger damage was done by lenders repricing over the autumn, and that's already in the numbers buyers are working with.

For buyers who can still get the numbers to stack up, less competition can mean more room to negotiate. For sellers, realistic pricing gets you moving. So there you have it: not doom and gloom, just a market that has to price in money costing a bit more.

FAQ: the November 2026 rate rise

What is the Bank of England base rate now?

4%, following the rise announced on 5 November 2026.

Does the rise affect my fixed-rate mortgage?

Not until your fixed deal ends. Tracker and variable rate borrowers feel it straight away.

How much does a 0.25% rise add to a mortgage?

Around £37 a month on a £250,000 repayment mortgage over 25 years, according to Moneyfacts.

When is the next rate decision?

The Bank of England's next announcement is due on Thursday 17 December 2026.

About me

I'm Jeroen Hoppe, an independent property specialist powered by eXp UK, with more than 20 years in property. I started at Ludlow Thompson (now Foxtons in South London), became a branch manager in under two years and won Manager of the Year two years after that. In 2011 I set up my own agency in Clapham and sold it to a local competitor in 2016. Since then I've worked in property development and investment as well as agency, and I've managed more than 40 units across long-term and short-term lets. I've been with eXp UK since mid-2023.

Are you buying, selling or remortgaging in Clapham, Battersea or Streatham this winter, and has the rate rise changed your plans? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: Bank of England, Monetary Policy Summary, November 2026, https://www.bankofengland.co.uk/monetary-policy-summary-and-minutes/2026/november-2026 ; Central Banking, Bank of England makes first rate hike since 2023 (5 November 2026) ; BBC News live coverage, 5 November 2026 ; Moneyfacts, Mortgage rates hit three-year high, BBR rise imminent (4 November 2026), https://www.moneyfactsgroup.co.uk/media-centre/consumer/mortgage-rates-hit-three-year-high-bbr-rise-imminent/ ; Bank of England, Monetary Policy Committee dates for 2026 and 2027, https://www.bankofengland.co.uk/monetary-policy/upcoming-mpc-dates ; Introducer Today and Estate Agent Today newsletters, 4-5 November 2026.

Uploaded Image

Tuesday, 3 November 2026

Do I need a landlord licence in Clapham, Brixton or Battersea? Lambeth, Wandsworth and Southwark explained

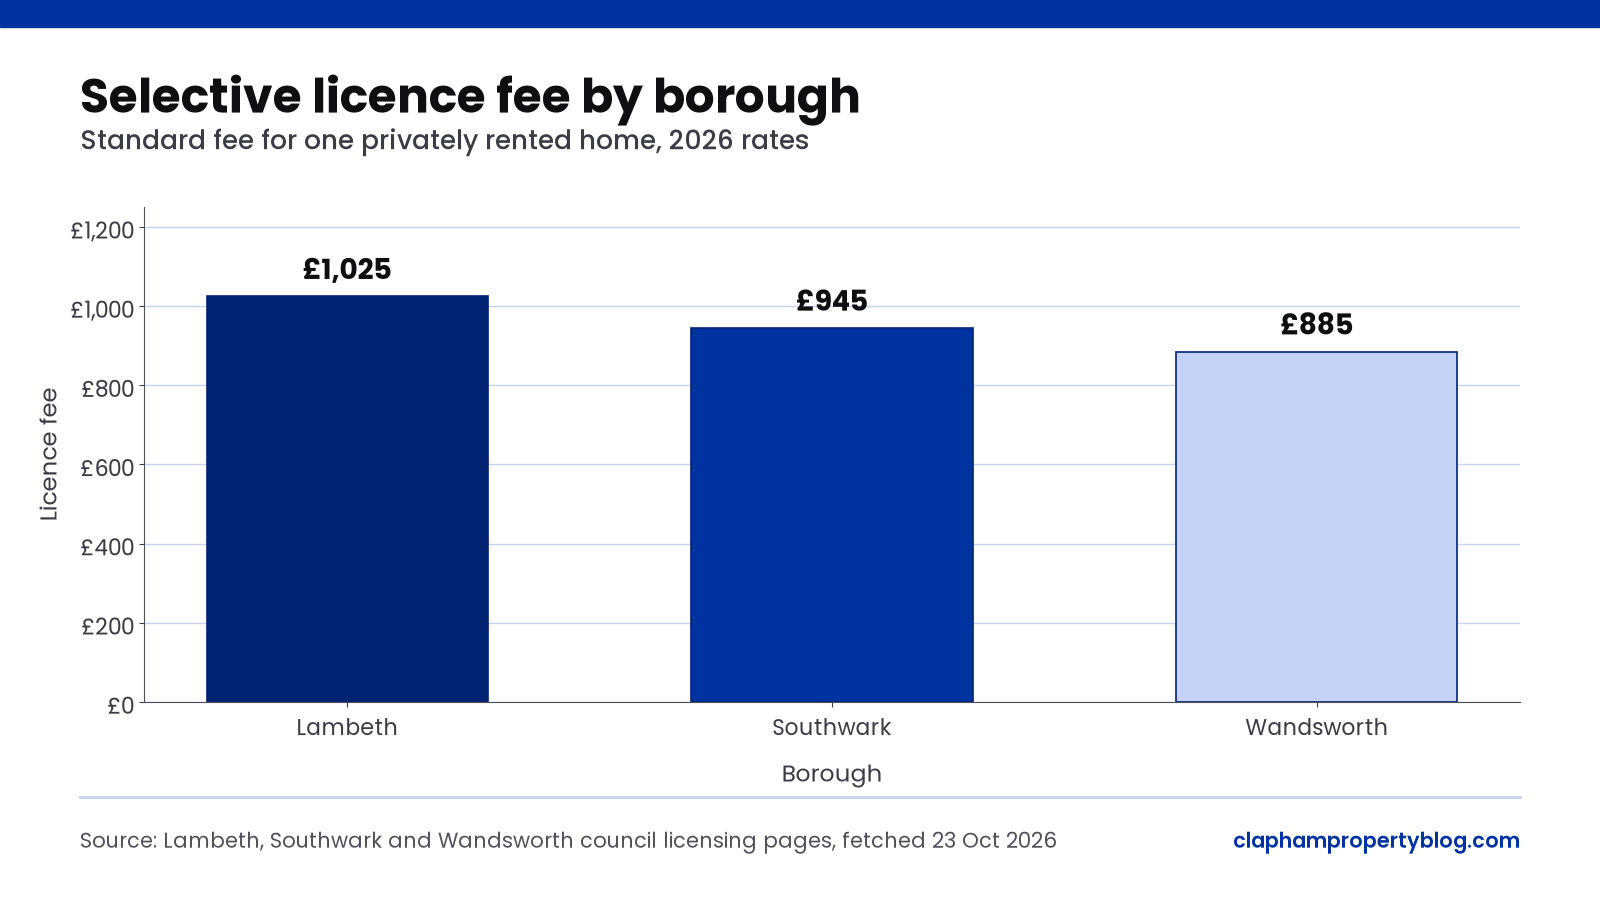
Selective licence fee by borough 2026: Lambeth £1,025, Southwark £945, Wandsworth £885

The question I get from landlords more than almost any other isn't about rents. It's "do I actually need a licence for my flat?"

Fair question. Each council runs its own schemes, with its own wards, fees and start dates, and a lot has changed since 2024. So here's the plain-English version for my patch, straight from the council websites.

Do I need a licence to rent out my property in South London?

In most of Lambeth, yes. In parts of Wandsworth and most of Southwark, yes. And if you let to sharers, almost certainly yes.

What types of landlord licence are there?

There are three types:

  • Mandatory HMO licence for larger shared houses. In Wandsworth that's five or more tenants from two or more households sharing a kitchen, bathroom or toilet.
  • Additional HMO licence for smaller shared homes the mandatory scheme doesn't catch, such as three or four sharers.
  • Selective licence for ordinary lets - a couple, a family, a single person - in the wards the council has designated.

Do I need a selective licence in Lambeth (Clapham, Brixton, Stockwell, Streatham)?

Almost certainly. Lambeth's selective licensing scheme covers any privately rented home let to a single-family household or to no more than two unrelated sharers (Lambeth Council).

Which Lambeth wards does selective licensing cover?

Phase 1 started on 2 September 2024 in four wards: Knights Hill and three Streatham wards. Phase 2 followed on 1 September 2025 with 19 more, including Clapham Common and Abbeville, Clapham Town, Clapham East, Clapham Park, all four Brixton wards, Stockwell East, Stockwell West and Larkhall, Herne Hill and Loughborough Junction, Kennington and Oval. Together they cover every Lambeth ward except Vauxhall and Waterloo & South Bank.

So if you let a flat off Abbeville Road, on Brixton Hill or near Stockwell station, assume you need a Lambeth selective licence.

How much is a selective licence in Lambeth?

Lambeth's selective licence fee is £1,025 from 1 April 2026: £717.50 when you apply and £307.50 once approved. There's £50 off for an EPC of C or better, and £75 off if you're accredited (NRLA, LLAS or UKALA, for example).

Do I need an HMO licence for a shared house in Lambeth?

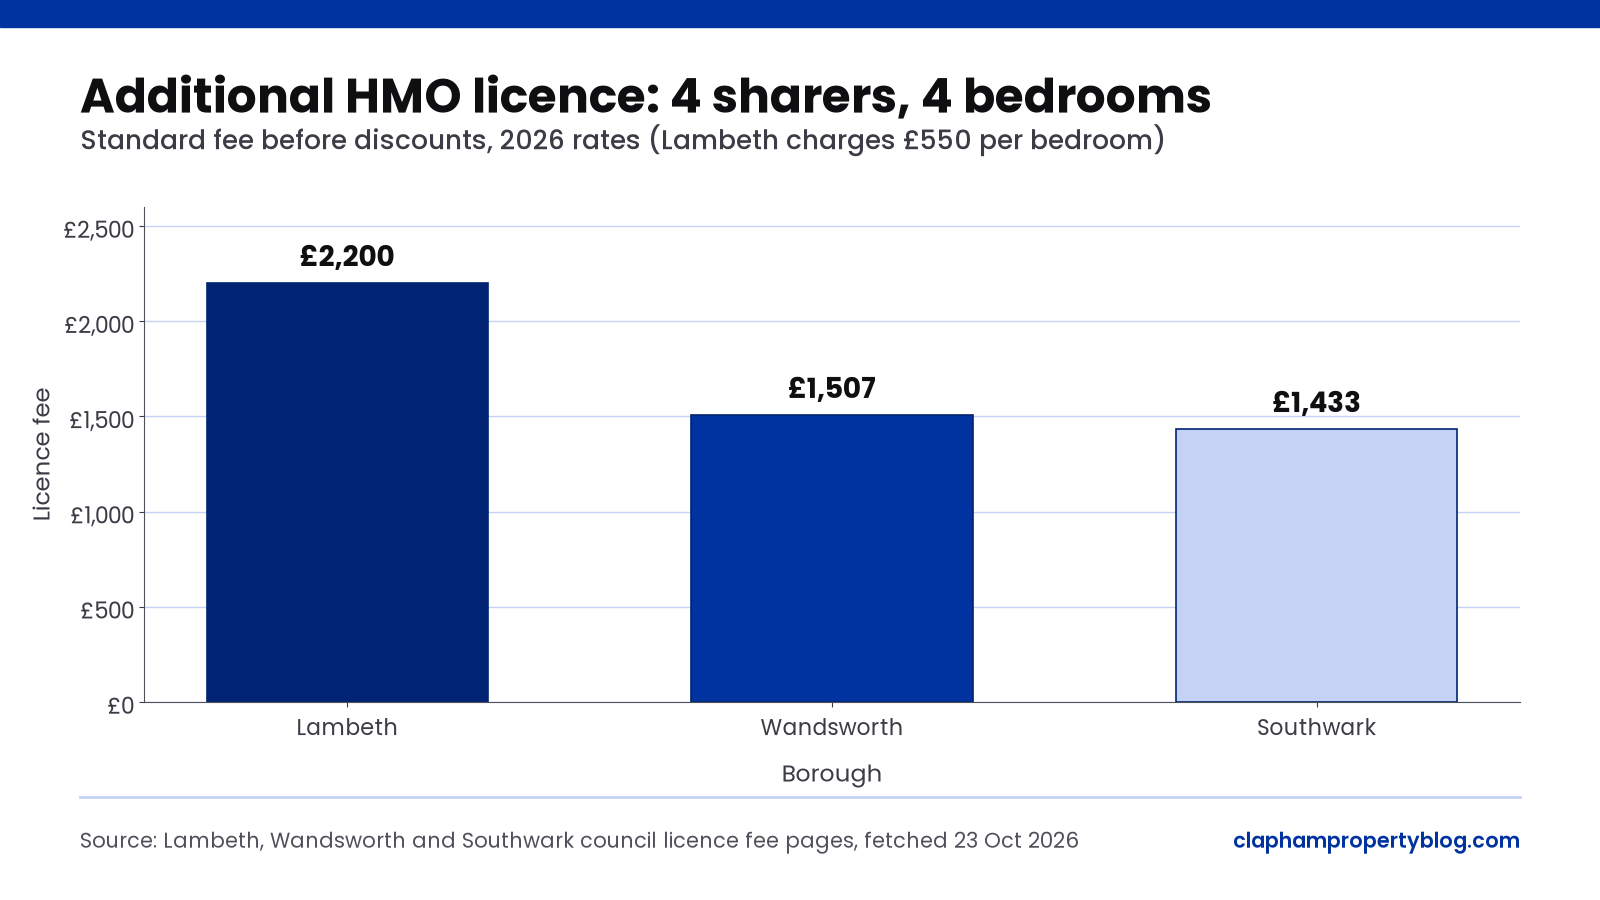
Yes. Lambeth has had borough-wide additional HMO licensing since 9 December 2021, for privately rented homes with three or more people forming two or more households. The fee is £550 per letting room, so a four-bedroom house share in Lambeth costs £2,200 to licence.

Additional HMO licence for 4 sharers, 2026: Lambeth £2,200, Wandsworth £1,507, Southwark £1,433

One date to watch: Lambeth's designation notice says the additional HMO scheme ceases on 8 December 2026. I couldn't find a replacement on the council's website at the time of writing, so check with Lambeth before assuming anything changes.

Do I need a selective licence in Wandsworth (Battersea, Balham, Tooting)?

Only in seven Wandsworth wards, for now. Wandsworth's first selective licensing designation covers Furzedown, Tooting Bec, Tooting Broadway and South Balham, and runs from 1 July 2025 to 30 June 2030. The second added East Putney, West Putney and Northcote from 1 April 2026, which takes in the Northcote Road end of Battersea (Wandsworth Council). The council confirmed to me in October 2026 that no other wards have been announced.

Outside those seven wards, you don't need a selective licence in Wandsworth.

Do I need an HMO licence for sharers in Wandsworth?

Yes, anywhere in the borough. Since 1 July 2025, Wandsworth HMOs let to up to four people sharing a bathroom or kitchen need an additional licence.

How much is a landlord licence in Wandsworth?

  • Selective licence: £885
  • Additional HMO licence: £1,507

Those are the totals on Wandsworth's property licence fees page, paid in two parts: one on application, one when the licence is granted.

The 30% early bird discount for Northcote and the Putney wards ended on 1 October 2026, so it's the full fee now. Wandsworth says a property licence usually lasts five years.

Do I need a licence in Southwark (Peckham, East Dulwich, Camberwell)?

Very likely. Southwark's selective licensing covers 19 wards, including Peckham, Peckham Rye, Rye Lane, Nunhead & Queens Road, Goose Green, Dulwich Hill, Champion Hill and Camberwell Green (Southwark Council). That's most of the SE15 and SE22 streets I work.

How much is a landlord licence in Southwark?

Southwark's licensing team confirmed to me in October 2026 that the selective licence fee is £945. The additional licence, for HMOs let to up to four people sharing facilities, is £1,433. Southwark's designation notices say the additional licensing scheme, and the selective licensing designations covering Champion Hill, Faraday, Goose Green, Newington and St Giles, end on 1 March 2027. The other 14 selective wards, including Peckham, Peckham Rye, Rye Lane, Nunhead & Queens Road, Dulwich Hill and Camberwell Green, run until 31 October 2028. Southwark's licensing team told me in October 2026 that a replacement will start from the day the current scheme expires.

What happens if I don't licence my rental property?

This is where it gets expensive. According to Lambeth Council, letting without a required licence is a criminal offence and can lead to:

  • prosecution and an unlimited fine
  • a financial penalty of up to £40,000 instead
  • a Rent Repayment Order of up to 24 months' rent
  • a banning order
  • a Section 8 possession claim that may not succeed

Put a £40,000 penalty next to Lambeth's £1,025 licence fee and it's not a difficult decision.

What documents does the council ask for in a licence application?

Lambeth's list is a good guide: Land Registry title dated within 28 days, gas safety certificate, EICR (with any C1 and C2 faults fixed and evidenced), EPC, an annotated floor plan and the tenancy agreement naming everyone living there. If your paperwork is ready for the new landlord register, you're most of the way there.

My take

Licensing is now the norm across my patch. Brixton, Clapham, Stockwell, Streatham, Tooting, Balham, Peckham and East Dulwich are all covered in some form. Good landlords have nothing to fear from it. It's a cost of doing business.

What worries me is the landlord with one flat who let it years ago and has no idea any of this happened. That's who ends up facing a Rent Repayment Order.

So there you have it. Check your ward, check your type of let, and apply before someone else points it out.

FAQ: landlord licensing in South London

How much does a landlord licence cost in Lambeth, Wandsworth and Southwark?

A selective licence costs £1,025 in Lambeth, £885 in Wandsworth and £945 in Southwark. For an additional HMO licence, Lambeth charges £550 per letting room, Wandsworth £1,507 and Southwark £1,433.

Is a landlord licence the same as the landlord register?

No. Licensing is run by your local council. The landlord register is a separate national requirement.

Who holds the landlord licence?

Usually the person who collects the rent and manages the property, says Wandsworth Council. That can be the owner or the manager.

How long does a landlord licence last?

Wandsworth Council says a property licence usually lasts five years.

How do I find out which ward my rental is in?

Use the council's postcode ward checker or licensing map. Lambeth, Wandsworth and Southwark all have one.

As always, are you a landlord in Clapham, Brixton or Battersea who isn't sure whether your let needs a licence? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

About me

I'm Jeroen Hoppe, an independent property specialist powered by eXp UK, with more than 20 years in property. I started at Ludlow Thompson (now Foxtons in South London), became a branch manager in under two years and won Manager of the Year two years after that. In 2011 I set up my own agency, XanderMatthew, in Clapham, and sold it to a local competitor in 2016. Since then I've worked in property development and investment as well as agency, and I've managed more than 40 units across long-term and short-term lets. I've been with eXp UK since mid-2023.

---------
07837 093 554

Sources: Lambeth Council, Selective Licensing Scheme and HMO licence fees pages (fees from 1 April 2026); Lambeth Council, Designation of an Area for Additional Licensing public notice (2021); Wandsworth Council, Check if you need a property licence and Property licence fees and discounts (updated 23 September 2026); Southwark Council, Selective licensing, Additional licensing and Licence fees pages (updated 10 March 2026) and its selective and additional licensing designation notices (2021 and 2023). All accessed 23 October 2026 and rechecked 3 November 2026. Email replies from Wandsworth Council and Southwark Council's licensing team, October 2026.

Sunday, 1 November 2026

A month on, Battersea's cladding queue hasn't moved

Battersea cladding queue - a month on

Last week I asked whether you should buy a modern flat now in Battersea. The new government cladding figures came out on 28 October, so I went straight to the Wandsworth line. Short answer: nothing has moved.

So what's happening?

The cold hard facts, from the government's September building safety release (figures to 30 September):

  • Across England, 4,732 buildings of 11 metres and over with unsafe cladding are now being monitored, eight more than in August.
  • 2,621 of them (55%) have started or finished works. 1,878 (40%) are finished, up from 1,849 (39%) a month earlier.
  • In Wandsworth, which covers Battersea and Nine Elms, there are still between 101 and 200 buildings on the list: 43% finished, 8% under way and 50% not started. In August it was 43%, 8% and 49%.

So England creeps forward, with 29 more buildings finished in a month. Wandsworth's finished share hasn't budged, and half the borough's listed buildings still haven't started work.

But what does it mean for Battersea?

Stuck buildings make nervous buyers. And nervous first-time buyers don't pick through a block flat by flat. They walk away from the whole building.

That's the mistake. Right now I'm seeing it on the patch: a good flat, a decent lease, a sensible service charge, and the buyer is gone the moment the word cladding comes up. That's my own observation, not a statistic. But that's exactly where value is being left on the table, because not every block on that list is the same. Some are fixed. Some are funded. Some genuinely are an open question. The trick is telling them apart.

Fixed, funded or open question?

Three things to ask before you fall in love, or walk away.

  • The EWS1 form. It isn't a safety certificate and it isn't a legal requirement. It's a form lenders and valuers may ask for, to judge whether work on the outside walls could affect value. If the building has one, ask what it says and when it was done. If your lender wants one and there isn't one, expect delays.
  • Who's paying. Ask the managing agent or freeholder which route the building is in: the developer, the Building Safety Fund, the Cladding Safety Scheme or the ACM programme. Lenders who signed up to the industry statement on cladding will lend on 11 metre plus buildings where the work is being done by the developer or through a government-funded scheme, or where the leaseholder protections in the Building Safety Act apply, backed by a leaseholder deed of certificate.
  • When work starts. Funded isn't finished. Get a start date and a finish date in writing.

Fixed, or funded with dates, and you're buying a flat. No EWS1, no scheme and no dates, and you're buying an open question. Price it that way, or don't buy.

Watch 5 November

The Bank of England's next rate decision is on 5 November. In September it held Bank Rate at 3.75%, and three of the nine committee members voted for a rise. If rates ease, the first-time buyers who walked away come back. If they don't, they stay on the sidelines and flat prices stay soft for longer.

Either way, the buyers who've done the homework go first. They already know which blocks are fixed, which are funded and which are open questions, and their offers are in before the crowd turns up.

My take

Wandsworth is stuck, but stuck isn't the same as hopeless. Don't buy a block on its brochure, and don't bin a block on a headline. Ask the three questions, get the answers in writing and let your solicitor and lender check them. This isn't financial advice, so take independent advice, of course.

The next government figures land on 25 November. I'll be checking the Wandsworth line again.

Are you looking at a Battersea or Nine Elms flat with a cladding question hanging over it, or sitting in one waiting for a start date? I'd genuinely like to hear how it's going. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: MHCLG Building Safety Remediation monthly data release, September 2026 (28 October 2026) and August 2026 (30 September 2026); MHCLG, Understanding fire risk appraisals of external walls in blocks of flats; MHCLG, Building Safety Fund: information for leaseholders and residents; UK Finance, Industry statement on cladding; Bank of England Monetary Policy Summary (17 September 2026).

Saturday, 31 October 2026

Your First Home: a 2.5% deposit scheme - but will it help first-time buyers in Clapham, Brixton and Streatham?

Your First Home 2.5% deposit scheme - what it means for Clapham, Brixton and Streatham

A 2.5% deposit. For first-time buyers in South London that sounds too good to be true. So what did the Budget actually confirm?

So what's happening?

The government has confirmed a new £4.7 billion equity loan scheme called Your First Home. It aims to help around 70,000 households in England onto the ladder. What GOV.UK has published so far:

  • You put down a deposit of at least 2.5%, up to a maximum of 15%.
  • The government lends you 20% of the price as an equity loan.
  • The rest is a repayment mortgage from a participating lender.
  • The equity loan is interest free for five years, then 1.5% in year six and 3% from year seven.
  • Household income must be £140,000 or less in London (£110,000 elsewhere).
  • Price caps are £650,000 in inner London and £500,000 in outer London.
  • It's for first-time buyers, for your main home, and only for new-build homes from developers signed up to the scheme.

Pre-registration opens by the end of December 2026, full applications from February 2027 and the first loans from April 2027.

The cold hard facts

Bear in mind it's an equity loan, not free money. If you borrow 20%, you pay back 20% of what the home is worth when you repay. GOV.UK's own example: buy at £300,000, borrow £60,000, and if the home is later valued at £320,000 you repay £64,000.

On a £500,000 new-build flat, that works out as:

  • Deposit (2.5%): £12,500
  • Equity loan (20%): £100,000
  • Mortgage: £387,500

You still need to pass the lender's affordability checks, of course.

But what does it mean for Clapham, Brixton and Streatham?

You see, here's the thing. Most of what first-time buyers buy round here is second-hand: period conversions off Abbeville Road, flats on Brixton Hill, mansion blocks in Streatham. None of that qualifies. This is a new-build scheme, full stop.

Where it could matter is new-build in Battersea and Nine Elms, plus the odd new block in Brixton or Streatham, if the developer signs up and the price sits under the cap. Lambeth and Wandsworth should count as inner London, but the full list of local caps isn't published yet, so I'd wait for that before getting excited.

Two more Budget changes worth knowing

  • Since 29 October 2026, you can use a Lifetime ISA on a home above the £450,000 cap with a 20% withdrawal charge instead of 25%. That's a real help in SW4, where £450,000 doesn't go far.
  • From April 2029, a new First Time Buyer ISA replaces the Lifetime ISA for new savers: up to £4,000 a year, a 25% bonus and no upper age limit.

My take

It's a genuine leg-up for buyers who'd happily take a new-build flat. But it does nothing for the period stock most people in Clapham and Brixton actually want, and an equity loan that grows with your home's value is a debt you'll need a plan to repay. Take independent advice first.

So there you have it. Would you buy a new-build to get on the ladder with just 2.5% down, or hold out for a period flat? Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: GOV.UK, Budget 2026 and "Your First Home" guidance (MHCLG), 28 October 2026.

Friday, 30 October 2026

Tenants told to 'flood' rent tribunals: a backdoor rent freeze that could backfire on Clapham and Battersea renters

Tenants told to flood rent tribunals - Clapham and Battersea

Let me say it straight. Telling tenants to challenge every rent rise, fair or not, isn't tenant protection. It's gaming the system, and in Clapham and Battersea it's renters who'll end up paying for it.

What's actually happening?

Under the Renters' Rights Act, in force since May, landlords can raise the rent only once a year, and tenants can challenge the increase at the First-tier Tribunal for £47. While the case runs, the tenant keeps paying the old rent.

The Telegraph reported last week that renters' unions in Oxford, London and Manchester are urging tenants to challenge rises even when they can afford them. Oxford Renters Union says decisions are taking five to six months. The more people apply, it says, the longer everyone pays the lower rent.

The case campaigners love

In Manchester, a landlord asked to go from £1,650 to £1,700 a month. The tribunal looked at the market evidence and set £1,450 instead. That's £2,400 a year less, not £600 more. The housing minister shared it on X as an example of the system working.

And in a way, it was. If the evidence says the rent is too high, the tenant should win. Propertymark's research shows tribunals weigh floor areas and room sizes differently by region, and outstanding repairs count against the landlord. Tired flats at top-of-the-market rents deserve to be challenged.

Where I part company with the campaigners

A safeguard against silly rent hikes is one thing. Clogging it up on purpose to create a backdoor rent freeze is another. The NRLA calls it using "the frailty in the system", and that's exactly what it is.

Here's the local maths. In my experience, a typical two-bed in Clapham and Battersea rents for around £2,500 a month. Say a landlord proposes a modest £75 rise, 3%. If a tactical challenge drags on for six months, that's £450 they never get back, even if the rise was fair all along.

Some landlords will shrug. Others will sell. Supply around here is tight enough already, and every flat that leaves the rental market means more people chasing fewer homes. That's the real cost of flooding the tribunals, and it lands on the next renter, not the landlord.

There's another catch. A system jammed with tactical cases is slower for the tenant facing a genuinely unfair jump, the very person it was built for.

Who wins and who loses?

  • Renters facing an above-market rise: challenge it. That's what the tribunal is for.
  • Fair landlords with the place in good repair: little to fear, but expect delay.
  • Landlords chasing top rents on tired flats: most exposed, and rightly so.

What I'd do now

  1. Build an evidence file before you serve the notice: three or four genuinely comparable lets, same size, same condition, same area.
  2. Fix any outstanding repairs first.
  3. Talk to your tenant before the paperwork. A modest, explained rise is far less likely to be challenged.

The good news? The Tenancy Deposit Scheme found 50% of landlords kept rents unchanged over the past 12 months, up from 39%. Plenty already prefer keeping a good tenant to squeezing one.

Over to you

Fair play or an own goal? Landlord or renter, I'd genuinely like to hear your view. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: The Telegraph, Property118, Landlord Law Newsround, Propertymark, Tenancy Deposit Scheme via Letting Agent Today and Property Reporter.

The first rate rise in three years: what 4% means for buyers, sellers and remortgagers in Clapham, Battersea and Streatham

Well, it finally happened. After ten meetings sitting on its hands, the Bank of England has put rates up. What did the Bank of England actu...

Popular Post!