Thursday, 12 November 2026

London asking rents are up 7.6%, but deals are being done 4.4% below: how renters and landlords in Clapham, Brixton and Streatham should play it

Read the headline and you'd think London rents were running away again. Read the small print and there's a very different story.

What are London rents doing?

Advertised London rents rose 7.6% year on year in October, to an average of £2,401 a month, according to lettings firm Hello Neighbour. That's six months in a row of annual growth since the Renters' Rights Act came in, and up from 6.1% in September.

So are tenants paying 7.6% more?

No. Those are asking rents on Hello Neighbour's own listings. On the London homes it listed from August to October that have since let, the agreed rent came in 4.4% below the advertised rent.

Other measures are calmer too. The ONS puts the average London rent at £2,338, up 3.5% in the 12 months to September. HomeLet, which tracks rents agreed on new tenancies, had London at £2,272 in September, up 3.3%.

Why are asking rents running ahead?

Partly the new rules. Under the Renters' Rights Act, landlords can't accept offers above the advertised rent, and rent increases are limited to once a year. So some landlords are listing high from the start. Supply plays its part as well: Zoopla says the number of London homes available to rent is 6% lower than a year earlier, and 13% lower in inner London.

Is demand cooling?

A little. Hello Neighbour's enquiries per property fell to 30 in October from 34 in September, against 56 in October 2024.

What does it mean for renters in Clapham, Brixton and Streatham?

The asking price is a starting point, not a verdict. Look at what similar flats have actually let for. In my experience across SW4, SW9 and SW16, well-priced flats are generally letting at the asking price, so the London-wide discount doesn't show up round here the same way. Offer below only where a flat has sat or looks overpriced.

What does it mean for landlords?

Over-pricing costs you twice. Every week empty is rent you never get back, and you can't make up for a weak start with a quick rise later. Increases come once a year through a section 13 notice, with two months' warning, and tenants can challenge them at tribunal.

A two-bed conversion off Brixton Hill or a one-bed near Streatham station priced right on day one will usually let faster to a better tenant than one sat on Rightmove waiting for a miracle.

My take

Here's the thing: across London, the headline number is the landlord's wish list and the agreed number is the market. Generation Rent has more bargaining power than the London headlines suggest. Round here, though, well-priced flats are usually letting at asking, so the discount is for the ones that have sat or been pitched too high. Good landlords should still welcome a well-priced, quick let over a long void.

So there you have it. Renters, negotiate where a flat has sat or looks overpriced. Landlords, price for the deal, not the headline.

FAQ: asking rents and agreed rents in London

What is the average asking rent in London?

£2,401 a month in October 2026 on Hello Neighbour's listings, up 7.6% on a year earlier.

Can I offer less than the advertised rent?

Yes. On Hello Neighbour's London lets from August to October, agreed rents averaged 4.4% below asking. Round here, well-priced flats are generally letting at asking, so an offer below makes most sense where a flat has sat or looks overpriced.

Can a landlord accept more than the asking rent?

No. Under the Renters' Rights Act, landlords can't accept offers above the advertised rent.

How often can my rent go up?

Once a year, through a section 13 notice with two months' notice, and you can challenge it at tribunal.

About me

I'm Jeroen Hoppe, an independent property specialist powered by eXp UK, with more than 20 years in property. I started at Ludlow Thompson (now Foxtons in South London), became a branch manager in under two years and won Manager of the Year two years after that. In 2011 I set up my own agency in Clapham and sold it to a local competitor in 2016. Since then I've worked in property development and investment as well as agency, and I've managed more than 40 units across long-term and short-term lets. I've been with eXp UK since mid-2023.

Are you a renter in Clapham, Brixton or Streatham weighing up whether to offer below asking, or a landlord pitching your next let? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: Hello Neighbour, London rental prices up 7.6% in October 2026, https://www.hello-neighbour.com/insights/hello-neighbour-insights-london-rental-prices-up-7.6-in-oct-26 ; Property Reporter, London rents rise 7.6% as supply tightens (5 November 2026), https://www.propertyreporter.co.uk/london-rents-rise-76-as-supply-tightens.html ; ONS, Private rent and house prices, UK: October 2026 ; HomeLet Rental Index, September 2026 ; Zoopla UK Rental Market Report, September 2026.


Jeroen Hoppe | Investor and Author
Clapham Property Blog
www.claphampropertyblog.com
Uploaded Image

Tuesday, 10 November 2026

The first rate rise in three years: what 4% means for buyers, sellers and remortgagers in Clapham, Battersea and Streatham

Well, it finally happened. After ten meetings sitting on its hands, the Bank of England has put rates up.

What did the Bank of England actually do?

On 5 November the Monetary Policy Committee voted 8-1 to raise Bank Rate by 0.25 percentage points, from 3.75% to 4%. The one dissenter, Catherine Mann, wanted to go further, to 4.25%. It's the first rise since August 2023.

Why did rates go up?

Energy. The Bank says the conflict in the Middle East has pushed energy prices up from an already high level. CPI inflation hit 3.5% in September and the Bank expects it to reach around 5% by the middle of next year.

Will there be more rises?

Governor Andrew Bailey told the BBC this shouldn't be seen as the first in an "inevitably long sequence of hikes", but "neither does it seem likely to be the last" unless the Iran war is resolved. So, not a straight answer. Truth of the matter is, nobody knows.

How much more will my mortgage cost?

Lenders moved before the Bank did. Moneyfacts says the average two-year fixed rate is now 5.97%, up from 4.83% at the start of 2026. On a £250,000 mortgage over 25 years, that's £169 a month more, or £2,028 a year, than a deal taken in January.

The 0.25% rise on its own adds around £37 a month on the same £250,000 loan, according to Moneyfacts. Tracker borrowers feel that first.

What does it mean for buyers in Clapham, Battersea and Streatham?

Bigger loans, bigger hit. A typical first-time buyer loan round here is about £400,000, which is a lot more than £250,000, so the monthly jump is bigger too. On that size of loan, the 0.25% rise alone is around £59 a month.

Lenders also test affordability at higher rates, so some buyers will find their budget has shrunk since the summer.

What does it mean for sellers?

Price for the buyer who exists today, not the one who existed in January. A buyer's mortgage offer sets the ceiling, and that ceiling has come down for many of them. Sellers Between the Commons or in Clapham Old Town with cash-rich or equity-rich buyers will feel it least.

What should I do if my fixed rate ends next year?

Moneyfacts suggests looking at a product transfer three to six months before your deal ends. Whatever you do, don't drift onto your lender's standard variable rate, which averages 7.13%. Take independent mortgage advice, of course.

My take

Let's face it, nobody enjoys a rate rise. But a quarter point isn't a crash. Bailey is hinting this is a nudge, not a sprint. The bigger damage was done by lenders repricing over the autumn, and that's already in the numbers buyers are working with.

For buyers who can still get the numbers to stack up, less competition can mean more room to negotiate. For sellers, realistic pricing gets you moving. So there you have it: not doom and gloom, just a market that has to price in money costing a bit more.

FAQ: the November 2026 rate rise

What is the Bank of England base rate now?

4%, following the rise announced on 5 November 2026.

Does the rise affect my fixed-rate mortgage?

Not until your fixed deal ends. Tracker and variable rate borrowers feel it straight away.

How much does a 0.25% rise add to a mortgage?

Around £37 a month on a £250,000 repayment mortgage over 25 years, according to Moneyfacts.

When is the next rate decision?

The Bank of England's next announcement is due on Thursday 17 December 2026.

About me

I'm Jeroen Hoppe, an independent property specialist powered by eXp UK, with more than 20 years in property. I started at Ludlow Thompson (now Foxtons in South London), became a branch manager in under two years and won Manager of the Year two years after that. In 2011 I set up my own agency in Clapham and sold it to a local competitor in 2016. Since then I've worked in property development and investment as well as agency, and I've managed more than 40 units across long-term and short-term lets. I've been with eXp UK since mid-2023.

Are you buying, selling or remortgaging in Clapham, Battersea or Streatham this winter, and has the rate rise changed your plans? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: Bank of England, Monetary Policy Summary, November 2026, https://www.bankofengland.co.uk/monetary-policy-summary-and-minutes/2026/november-2026 ; Central Banking, Bank of England makes first rate hike since 2023 (5 November 2026) ; BBC News live coverage, 5 November 2026 ; Moneyfacts, Mortgage rates hit three-year high, BBR rise imminent (4 November 2026), https://www.moneyfactsgroup.co.uk/media-centre/consumer/mortgage-rates-hit-three-year-high-bbr-rise-imminent/ ; Bank of England, Monetary Policy Committee dates for 2026 and 2027, https://www.bankofengland.co.uk/monetary-policy/upcoming-mpc-dates ; Introducer Today and Estate Agent Today newsletters, 4-5 November 2026.

Uploaded Image

Tuesday, 3 November 2026

Do I need a landlord licence in Clapham, Brixton or Battersea? Lambeth, Wandsworth and Southwark explained

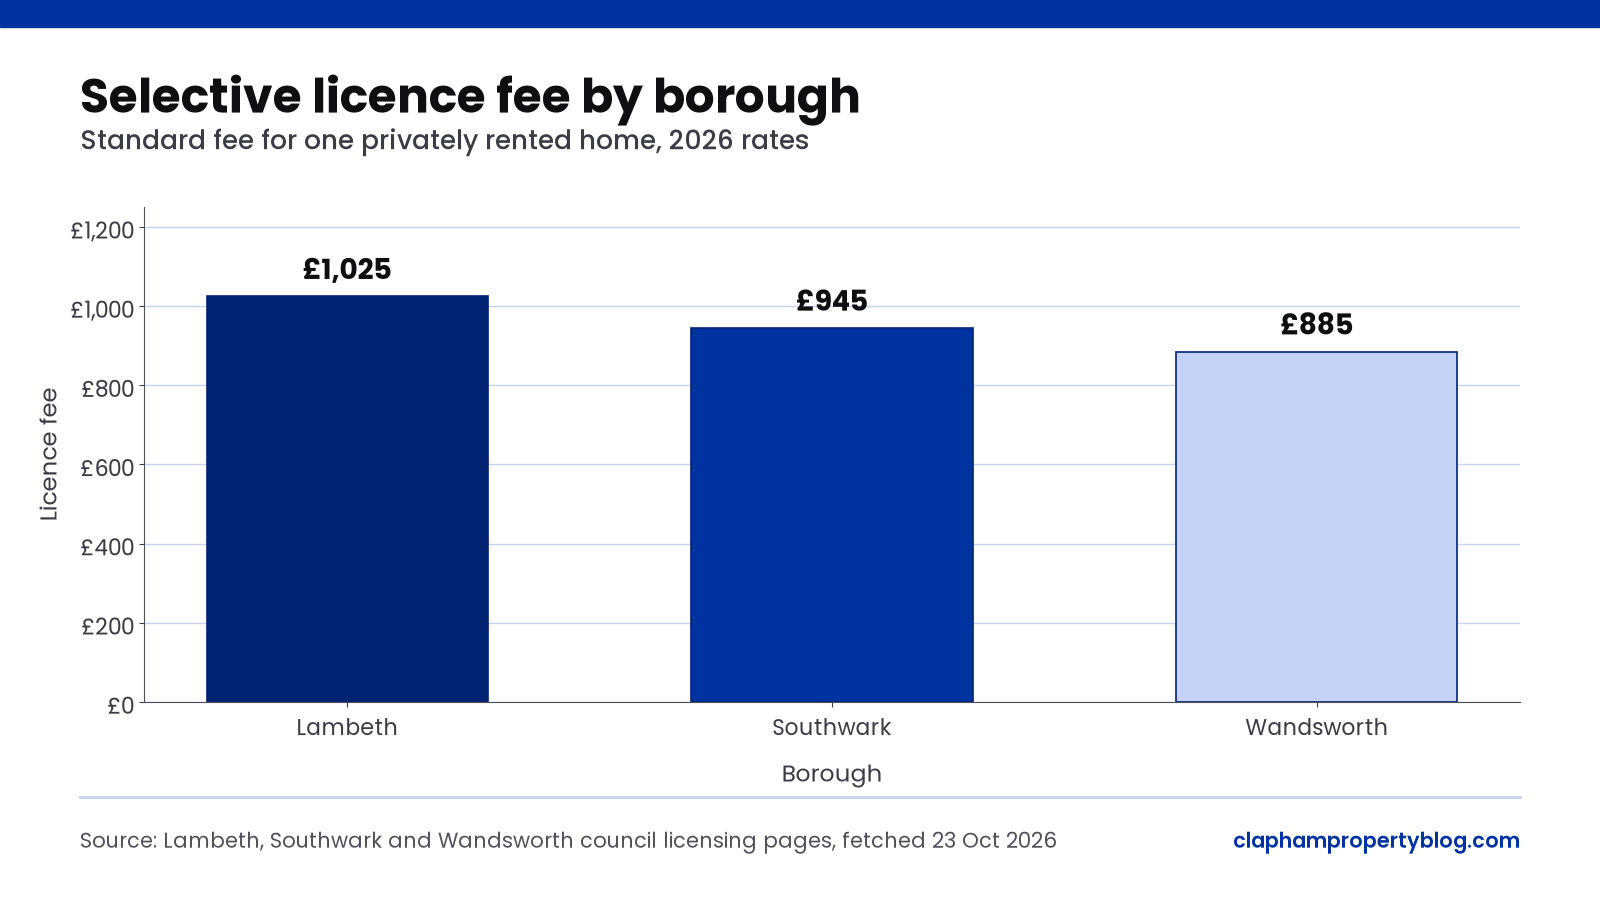
Selective licence fee by borough 2026: Lambeth £1,025, Southwark £945, Wandsworth £885

The question I get from landlords more than almost any other isn't about rents. It's "do I actually need a licence for my flat?"

Fair question. Each council runs its own schemes, with its own wards, fees and start dates, and a lot has changed since 2024. So here's the plain-English version for my patch, straight from the council websites.

Do I need a licence to rent out my property in South London?

In most of Lambeth, yes. In parts of Wandsworth and most of Southwark, yes. And if you let to sharers, almost certainly yes.

What types of landlord licence are there?

There are three types:

  • Mandatory HMO licence for larger shared houses. In Wandsworth that's five or more tenants from two or more households sharing a kitchen, bathroom or toilet.
  • Additional HMO licence for smaller shared homes the mandatory scheme doesn't catch, such as three or four sharers.
  • Selective licence for ordinary lets - a couple, a family, a single person - in the wards the council has designated.

Do I need a selective licence in Lambeth (Clapham, Brixton, Stockwell, Streatham)?

Almost certainly. Lambeth's selective licensing scheme covers any privately rented home let to a single-family household or to no more than two unrelated sharers (Lambeth Council).

Which Lambeth wards does selective licensing cover?

Phase 1 started on 2 September 2024 in four wards: Knights Hill and three Streatham wards. Phase 2 followed on 1 September 2025 with 19 more, including Clapham Common and Abbeville, Clapham Town, Clapham East, Clapham Park, all four Brixton wards, Stockwell East, Stockwell West and Larkhall, Herne Hill and Loughborough Junction, Kennington and Oval. Together they cover every Lambeth ward except Vauxhall and Waterloo & South Bank.

So if you let a flat off Abbeville Road, on Brixton Hill or near Stockwell station, assume you need a Lambeth selective licence.

How much is a selective licence in Lambeth?

Lambeth's selective licence fee is £1,025 from 1 April 2026: £717.50 when you apply and £307.50 once approved. There's £50 off for an EPC of C or better, and £75 off if you're accredited (NRLA, LLAS or UKALA, for example).

Do I need an HMO licence for a shared house in Lambeth?

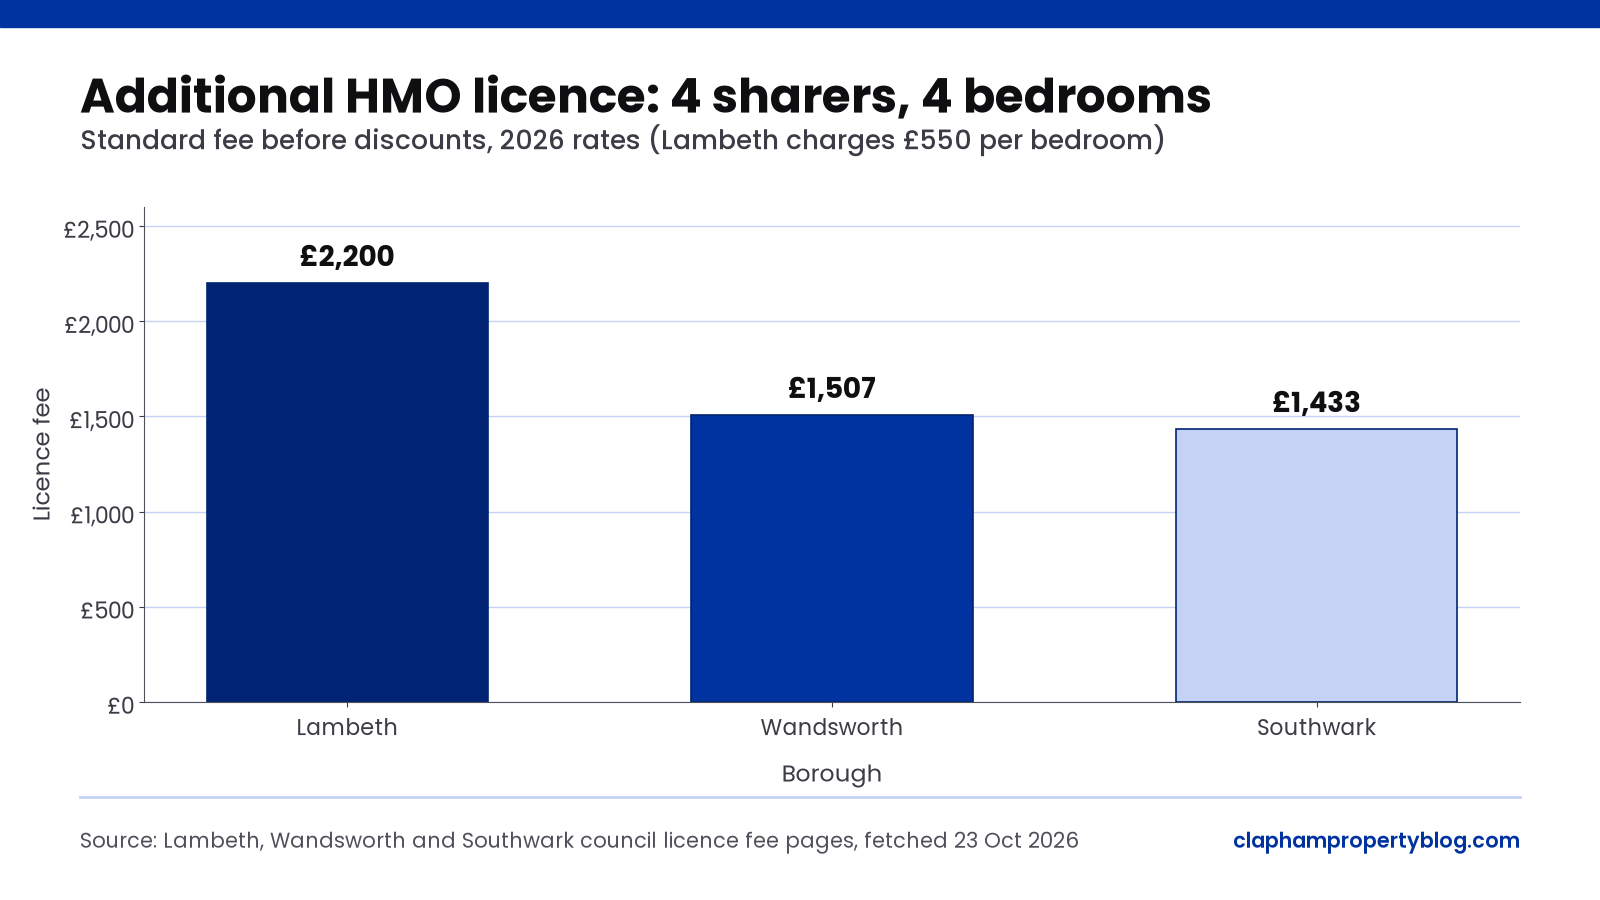
Yes. Lambeth has had borough-wide additional HMO licensing since 9 December 2021, for privately rented homes with three or more people forming two or more households. The fee is £550 per letting room, so a four-bedroom house share in Lambeth costs £2,200 to licence.

Additional HMO licence for 4 sharers, 2026: Lambeth £2,200, Wandsworth £1,507, Southwark £1,433

One date to watch: Lambeth's designation notice says the additional HMO scheme ceases on 8 December 2026. I couldn't find a replacement on the council's website at the time of writing, so check with Lambeth before assuming anything changes.

Do I need a selective licence in Wandsworth (Battersea, Balham, Tooting)?

Only in seven Wandsworth wards, for now. Wandsworth's first selective licensing designation covers Furzedown, Tooting Bec, Tooting Broadway and South Balham, and runs from 1 July 2025 to 30 June 2030. The second added East Putney, West Putney and Northcote from 1 April 2026, which takes in the Northcote Road end of Battersea (Wandsworth Council). The council confirmed to me in October 2026 that no other wards have been announced.

Outside those seven wards, you don't need a selective licence in Wandsworth.

Do I need an HMO licence for sharers in Wandsworth?

Yes, anywhere in the borough. Since 1 July 2025, Wandsworth HMOs let to up to four people sharing a bathroom or kitchen need an additional licence.

How much is a landlord licence in Wandsworth?

  • Selective licence: £885
  • Additional HMO licence: £1,507

Those are the totals on Wandsworth's property licence fees page, paid in two parts: one on application, one when the licence is granted.

The 30% early bird discount for Northcote and the Putney wards ended on 1 October 2026, so it's the full fee now. Wandsworth says a property licence usually lasts five years.

Do I need a licence in Southwark (Peckham, East Dulwich, Camberwell)?

Very likely. Southwark's selective licensing covers 19 wards, including Peckham, Peckham Rye, Rye Lane, Nunhead & Queens Road, Goose Green, Dulwich Hill, Champion Hill and Camberwell Green (Southwark Council). That's most of the SE15 and SE22 streets I work.

How much is a landlord licence in Southwark?

Southwark's licensing team confirmed to me in October 2026 that the selective licence fee is £945. The additional licence, for HMOs let to up to four people sharing facilities, is £1,433. Southwark's designation notices say the additional licensing scheme, and the selective licensing designations covering Champion Hill, Faraday, Goose Green, Newington and St Giles, end on 1 March 2027. The other 14 selective wards, including Peckham, Peckham Rye, Rye Lane, Nunhead & Queens Road, Dulwich Hill and Camberwell Green, run until 31 October 2028. Southwark's licensing team told me in October 2026 that a replacement will start from the day the current scheme expires.

What happens if I don't licence my rental property?

This is where it gets expensive. According to Lambeth Council, letting without a required licence is a criminal offence and can lead to:

  • prosecution and an unlimited fine
  • a financial penalty of up to £40,000 instead
  • a Rent Repayment Order of up to 24 months' rent
  • a banning order
  • a Section 8 possession claim that may not succeed

Put a £40,000 penalty next to Lambeth's £1,025 licence fee and it's not a difficult decision.

What documents does the council ask for in a licence application?

Lambeth's list is a good guide: Land Registry title dated within 28 days, gas safety certificate, EICR (with any C1 and C2 faults fixed and evidenced), EPC, an annotated floor plan and the tenancy agreement naming everyone living there. If your paperwork is ready for the new landlord register, you're most of the way there.

My take

Licensing is now the norm across my patch. Brixton, Clapham, Stockwell, Streatham, Tooting, Balham, Peckham and East Dulwich are all covered in some form. Good landlords have nothing to fear from it. It's a cost of doing business.

What worries me is the landlord with one flat who let it years ago and has no idea any of this happened. That's who ends up facing a Rent Repayment Order.

So there you have it. Check your ward, check your type of let, and apply before someone else points it out.

FAQ: landlord licensing in South London

How much does a landlord licence cost in Lambeth, Wandsworth and Southwark?

A selective licence costs £1,025 in Lambeth, £885 in Wandsworth and £945 in Southwark. For an additional HMO licence, Lambeth charges £550 per letting room, Wandsworth £1,507 and Southwark £1,433.

Is a landlord licence the same as the landlord register?

No. Licensing is run by your local council. The landlord register is a separate national requirement.

Who holds the landlord licence?

Usually the person who collects the rent and manages the property, says Wandsworth Council. That can be the owner or the manager.

How long does a landlord licence last?

Wandsworth Council says a property licence usually lasts five years.

How do I find out which ward my rental is in?

Use the council's postcode ward checker or licensing map. Lambeth, Wandsworth and Southwark all have one.

As always, are you a landlord in Clapham, Brixton or Battersea who isn't sure whether your let needs a licence? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

About me

I'm Jeroen Hoppe, an independent property specialist powered by eXp UK, with more than 20 years in property. I started at Ludlow Thompson (now Foxtons in South London), became a branch manager in under two years and won Manager of the Year two years after that. In 2011 I set up my own agency, XanderMatthew, in Clapham, and sold it to a local competitor in 2016. Since then I've worked in property development and investment as well as agency, and I've managed more than 40 units across long-term and short-term lets. I've been with eXp UK since mid-2023.

---------
07837 093 554

Sources: Lambeth Council, Selective Licensing Scheme and HMO licence fees pages (fees from 1 April 2026); Lambeth Council, Designation of an Area for Additional Licensing public notice (2021); Wandsworth Council, Check if you need a property licence and Property licence fees and discounts (updated 23 September 2026); Southwark Council, Selective licensing, Additional licensing and Licence fees pages (updated 10 March 2026) and its selective and additional licensing designation notices (2021 and 2023). All accessed 23 October 2026 and rechecked 3 November 2026. Email replies from Wandsworth Council and Southwark Council's licensing team, October 2026.

Sunday, 1 November 2026

A month on, Battersea's cladding queue hasn't moved

Battersea cladding queue - a month on

Last week I asked whether you should buy a modern flat now in Battersea. The new government cladding figures came out on 28 October, so I went straight to the Wandsworth line. Short answer: nothing has moved.

So what's happening?

The cold hard facts, from the government's September building safety release (figures to 30 September):

  • Across England, 4,732 buildings of 11 metres and over with unsafe cladding are now being monitored, eight more than in August.
  • 2,621 of them (55%) have started or finished works. 1,878 (40%) are finished, up from 1,849 (39%) a month earlier.
  • In Wandsworth, which covers Battersea and Nine Elms, there are still between 101 and 200 buildings on the list: 43% finished, 8% under way and 50% not started. In August it was 43%, 8% and 49%.

So England creeps forward, with 29 more buildings finished in a month. Wandsworth's finished share hasn't budged, and half the borough's listed buildings still haven't started work.

But what does it mean for Battersea?

Stuck buildings make nervous buyers. And nervous first-time buyers don't pick through a block flat by flat. They walk away from the whole building.

That's the mistake. Right now I'm seeing it on the patch: a good flat, a decent lease, a sensible service charge, and the buyer is gone the moment the word cladding comes up. That's my own observation, not a statistic. But that's exactly where value is being left on the table, because not every block on that list is the same. Some are fixed. Some are funded. Some genuinely are an open question. The trick is telling them apart.

Fixed, funded or open question?

Three things to ask before you fall in love, or walk away.

  • The EWS1 form. It isn't a safety certificate and it isn't a legal requirement. It's a form lenders and valuers may ask for, to judge whether work on the outside walls could affect value. If the building has one, ask what it says and when it was done. If your lender wants one and there isn't one, expect delays.
  • Who's paying. Ask the managing agent or freeholder which route the building is in: the developer, the Building Safety Fund, the Cladding Safety Scheme or the ACM programme. Lenders who signed up to the industry statement on cladding will lend on 11 metre plus buildings where the work is being done by the developer or through a government-funded scheme, or where the leaseholder protections in the Building Safety Act apply, backed by a leaseholder deed of certificate.
  • When work starts. Funded isn't finished. Get a start date and a finish date in writing.

Fixed, or funded with dates, and you're buying a flat. No EWS1, no scheme and no dates, and you're buying an open question. Price it that way, or don't buy.

Watch 5 November

The Bank of England's next rate decision is on 5 November. In September it held Bank Rate at 3.75%, and three of the nine committee members voted for a rise. If rates ease, the first-time buyers who walked away come back. If they don't, they stay on the sidelines and flat prices stay soft for longer.

Either way, the buyers who've done the homework go first. They already know which blocks are fixed, which are funded and which are open questions, and their offers are in before the crowd turns up.

My take

Wandsworth is stuck, but stuck isn't the same as hopeless. Don't buy a block on its brochure, and don't bin a block on a headline. Ask the three questions, get the answers in writing and let your solicitor and lender check them. This isn't financial advice, so take independent advice, of course.

The next government figures land on 25 November. I'll be checking the Wandsworth line again.

Are you looking at a Battersea or Nine Elms flat with a cladding question hanging over it, or sitting in one waiting for a start date? I'd genuinely like to hear how it's going. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: MHCLG Building Safety Remediation monthly data release, September 2026 (28 October 2026) and August 2026 (30 September 2026); MHCLG, Understanding fire risk appraisals of external walls in blocks of flats; MHCLG, Building Safety Fund: information for leaseholders and residents; UK Finance, Industry statement on cladding; Bank of England Monetary Policy Summary (17 September 2026).

Saturday, 31 October 2026

Your First Home: a 2.5% deposit scheme - but will it help first-time buyers in Clapham, Brixton and Streatham?

Your First Home 2.5% deposit scheme - what it means for Clapham, Brixton and Streatham

A 2.5% deposit. For first-time buyers in South London that sounds too good to be true. So what did the Budget actually confirm?

So what's happening?

The government has confirmed a new £4.7 billion equity loan scheme called Your First Home. It aims to help around 70,000 households in England onto the ladder. What GOV.UK has published so far:

  • You put down a deposit of at least 2.5%, up to a maximum of 15%.
  • The government lends you 20% of the price as an equity loan.
  • The rest is a repayment mortgage from a participating lender.
  • The equity loan is interest free for five years, then 1.5% in year six and 3% from year seven.
  • Household income must be £140,000 or less in London (£110,000 elsewhere).
  • Price caps are £650,000 in inner London and £500,000 in outer London.
  • It's for first-time buyers, for your main home, and only for new-build homes from developers signed up to the scheme.

Pre-registration opens by the end of December 2026, full applications from February 2027 and the first loans from April 2027.

The cold hard facts

Bear in mind it's an equity loan, not free money. If you borrow 20%, you pay back 20% of what the home is worth when you repay. GOV.UK's own example: buy at £300,000, borrow £60,000, and if the home is later valued at £320,000 you repay £64,000.

On a £500,000 new-build flat, that works out as:

  • Deposit (2.5%): £12,500
  • Equity loan (20%): £100,000
  • Mortgage: £387,500

You still need to pass the lender's affordability checks, of course.

But what does it mean for Clapham, Brixton and Streatham?

You see, here's the thing. Most of what first-time buyers buy round here is second-hand: period conversions off Abbeville Road, flats on Brixton Hill, mansion blocks in Streatham. None of that qualifies. This is a new-build scheme, full stop.

Where it could matter is new-build in Battersea and Nine Elms, plus the odd new block in Brixton or Streatham, if the developer signs up and the price sits under the cap. Lambeth and Wandsworth should count as inner London, but the full list of local caps isn't published yet, so I'd wait for that before getting excited.

Two more Budget changes worth knowing

  • Since 29 October 2026, you can use a Lifetime ISA on a home above the £450,000 cap with a 20% withdrawal charge instead of 25%. That's a real help in SW4, where £450,000 doesn't go far.
  • From April 2029, a new First Time Buyer ISA replaces the Lifetime ISA for new savers: up to £4,000 a year, a 25% bonus and no upper age limit.

My take

It's a genuine leg-up for buyers who'd happily take a new-build flat. But it does nothing for the period stock most people in Clapham and Brixton actually want, and an equity loan that grows with your home's value is a debt you'll need a plan to repay. Take independent advice first.

So there you have it. Would you buy a new-build to get on the ladder with just 2.5% down, or hold out for a period flat? Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: GOV.UK, Budget 2026 and "Your First Home" guidance (MHCLG), 28 October 2026.

Friday, 30 October 2026

Tenants told to 'flood' rent tribunals: a backdoor rent freeze that could backfire on Clapham and Battersea renters

Tenants told to flood rent tribunals - Clapham and Battersea

Let me say it straight. Telling tenants to challenge every rent rise, fair or not, isn't tenant protection. It's gaming the system, and in Clapham and Battersea it's renters who'll end up paying for it.

What's actually happening?

Under the Renters' Rights Act, in force since May, landlords can raise the rent only once a year, and tenants can challenge the increase at the First-tier Tribunal for £47. While the case runs, the tenant keeps paying the old rent.

The Telegraph reported last week that renters' unions in Oxford, London and Manchester are urging tenants to challenge rises even when they can afford them. Oxford Renters Union says decisions are taking five to six months. The more people apply, it says, the longer everyone pays the lower rent.

The case campaigners love

In Manchester, a landlord asked to go from £1,650 to £1,700 a month. The tribunal looked at the market evidence and set £1,450 instead. That's £2,400 a year less, not £600 more. The housing minister shared it on X as an example of the system working.

And in a way, it was. If the evidence says the rent is too high, the tenant should win. Propertymark's research shows tribunals weigh floor areas and room sizes differently by region, and outstanding repairs count against the landlord. Tired flats at top-of-the-market rents deserve to be challenged.

Where I part company with the campaigners

A safeguard against silly rent hikes is one thing. Clogging it up on purpose to create a backdoor rent freeze is another. The NRLA calls it using "the frailty in the system", and that's exactly what it is.

Here's the local maths. In my experience, a typical two-bed in Clapham and Battersea rents for around £2,500 a month. Say a landlord proposes a modest £75 rise, 3%. If a tactical challenge drags on for six months, that's £450 they never get back, even if the rise was fair all along.

Some landlords will shrug. Others will sell. Supply around here is tight enough already, and every flat that leaves the rental market means more people chasing fewer homes. That's the real cost of flooding the tribunals, and it lands on the next renter, not the landlord.

There's another catch. A system jammed with tactical cases is slower for the tenant facing a genuinely unfair jump, the very person it was built for.

Who wins and who loses?

  • Renters facing an above-market rise: challenge it. That's what the tribunal is for.
  • Fair landlords with the place in good repair: little to fear, but expect delay.
  • Landlords chasing top rents on tired flats: most exposed, and rightly so.

What I'd do now

  1. Build an evidence file before you serve the notice: three or four genuinely comparable lets, same size, same condition, same area.
  2. Fix any outstanding repairs first.
  3. Talk to your tenant before the paperwork. A modest, explained rise is far less likely to be challenged.

The good news? The Tenancy Deposit Scheme found 50% of landlords kept rents unchanged over the past 12 months, up from 39%. Plenty already prefer keeping a good tenant to squeezing one.

Over to you

Fair play or an own goal? Landlord or renter, I'd genuinely like to hear your view. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: The Telegraph, Property118, Landlord Law Newsround, Propertymark, Tenancy Deposit Scheme via Letting Agent Today and Property Reporter.

Thursday, 29 October 2026

Landlord licensing is changing again. I'm not waiting to find out the hard way

Landlord licensing is changing again - Clapham, Brixton, Battersea and Peckham

Landlord licensing in South London has changed a lot in the last two years, and it's about to change again. So this week, rather than waiting for a letter from the council to land on a landlord's doormat, I got on the front foot.

What's changing?

A quick recap of where my patch stands:

  • Lambeth extended selective licensing to Clapham, Brixton, Stockwell and Kennington in September 2025, so it now covers every ward except Vauxhall and Waterloo & South Bank. Its borough-wide additional HMO scheme, for shared houses, is due to end on 8 December 2026, and I couldn't find a replacement on the council's website.
  • Wandsworth started selective licensing in Furzedown, Tooting Bec, Tooting Broadway and South Balham in July 2025, and added Northcote, East Putney and West Putney in April 2026. The council has confirmed to me that no further wards have been announced. Shared houses with up to four sharers now need an additional licence anywhere in the borough.
  • Southwark covers 19 wards, including most of Peckham and East Dulwich. The council has confirmed its fees are £945 for a selective licence and £1,433 for an additional licence. The current scheme runs until 2027, and a replacement will start from the day it expires.
  • Lewisham has had selective licensing across most of the borough since July 2024, and the council has told me its additional HMO scheme carries on for the foreseeable future.

Fees run from about £640 to over £1,500, and in Lambeth the penalties for getting it wrong include a fine of up to £40,000 and having to pay back up to 24 months' rent. That is not a letter anyone wants to open.

So what have I done?

Two things.

First, I've written to the licensing teams at Lambeth, Wandsworth, Southwark and Lewisham. I've asked each one what happens next: are schemes being renewed, are new wards coming in, are fees changing, and what happens to licences that run past the end of a scheme.

Second, I'm writing to every landlord I look after in Lambeth and Wandsworth. Each one will hear where their property stands under their council's scheme, and that I'm already chasing the council for answers on their behalf.

No landlord of mine should have to find out from a council enforcement officer that the rules changed.

Why bother?

Here's the thing. Most of this isn't strictly my job. A landlord holds their own licence. But a good agent spots what's coming before it becomes a problem, and these schemes are exactly the kind of thing a busy landlord with one or two flats can easily miss.

That's the difference between an agent who collects rent and one who actually looks after your investment.

What happens next?

Wandsworth, Lewisham and Southwark have already replied, and the details above reflect what they told me. Lambeth is still due. As soon as they reply, I'll update my landlords, and I'll share what I learn here too. If you're a landlord in Clapham, Brixton, Battersea, Peckham or Lewisham and you're not sure whether your let is licensed, or whether your licence is about to be caught out by a scheme ending, I'm happy to take a look. No strings attached.

So there you have it. The rules keep moving, and I'd rather be a step ahead than a step behind.

As always, are you a landlord who isn't sure where your property stands? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: Lambeth Council, Selective Licensing Scheme and additional licensing designation notice; Wandsworth Council, Check if you need a property licence; Southwark Council, Private rented property licensing pages; Lewisham Council, Selective licensing page; email replies from Wandsworth Council (Merton, Richmond and Wandsworth regulatory services), Lewisham Council and Southwark Council's licensing team, October 2026. All accessed 23 October 2026.

Wednesday, 28 October 2026

Most first-time buyers now pay more than they did in rent: is buying in Clapham, Brixton or Streatham still worth it?

Most first-time buyers now pay more than they did in rent - Clapham, Brixton and Streatham

For years the maths was simple. Saving the deposit was the hard part, but once you had the keys, your mortgage was usually cheaper than your rent. Not any more.

The cold hard facts

Hamptons, using Connells Group data, found that 56% of first-time buyers who bought in September took on a mortgage payment higher than the rent they left behind. That's the highest share in at least a decade, up from 33% in September 2022.

  • The average first-time buyer's mortgage payment was £1,227 a month, £39 (8.6%) more than their old rent.
  • Those paying more had borrowed at an average 91% loan-to-value, a 9% deposit. Those paying less had a 17% deposit.
  • Buyers in their 40s paid 18.2% more than their old rent. Buyers in their 20s still paid 7.5% less.

Why? Mortgage rates. Since the conflict in the Middle East pushed up swap rates, the average five-year fix has passed 6% for the first time in three years, according to reports. Moneyfacts says the average mortgage deal now stays on sale for just 13 days before it's pulled or repriced.

These are national figures, of course. Here, the numbers are bigger.

So what does it mean for Clapham, Brixton and Streatham?

Hamptons puts the average new let in Greater London at £2,357 a month, up 1.5% on a year ago. Renters in a one-bed off Clapham High Street or a two-bed near Brixton tube will know that number well.

Closer to home, the latest UK House Price Index puts the average price paid by a first-time buyer in Lambeth, which covers most of Clapham, Brixton and Streatham, at £474,320 in August. On rent, my own view is that a typical one-bed round here goes for £1,800 to £2,200 a month.

Who wins and who loses locally?

  • Buyers with a bigger deposit (often thanks to the Bank of Mum and Dad) are still likely to pay less than rent, and they're buying in a market with more stock and more room to negotiate.
  • Buyers stretching on a 5% or 10% deposit will feel the monthly pinch, at least until rates come down.
  • Sellers of one and two-bed flats need to remember who their buyer is. If the monthly maths doesn't work for them, the price has to.

What I'd do now

  1. Run your own numbers: mortgage, service charge and ground rent on a flat, against what you pay in rent today.
  2. Get a mortgage in principle early and be ready to move fast. Deals are disappearing in under a fortnight.
  3. Look at the bigger picture. Every mortgage payment chips away at a debt. Rent doesn't.

My take

The headline sounds gloomy, but I'd read it differently. Paying £39 a month more for a home you own, with security and equity building, isn't a bad deal compared with renting in London, where rents keep rising. The real squeeze is on deposits, not on the principle of buying.

And with this week's Budget and the Bank of England's next meeting in November, rates could move either way. Waiting for the perfect moment rarely works.

So there you have it. Buying costs a bit more each month than it did, but it's still building something.

Are you renting in Clapham or Brixton and wondering whether to make the jump? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: Hamptons (Connells Group data), HM Land Registry / ONS UK House Price Index (August 2026), Moneyfacts via Introducer Today, The Guardian, Property Reporter, Estate Agent Today.

Tuesday, 27 October 2026

House prices and rents in Clapham, Brixton & Battersea 2026

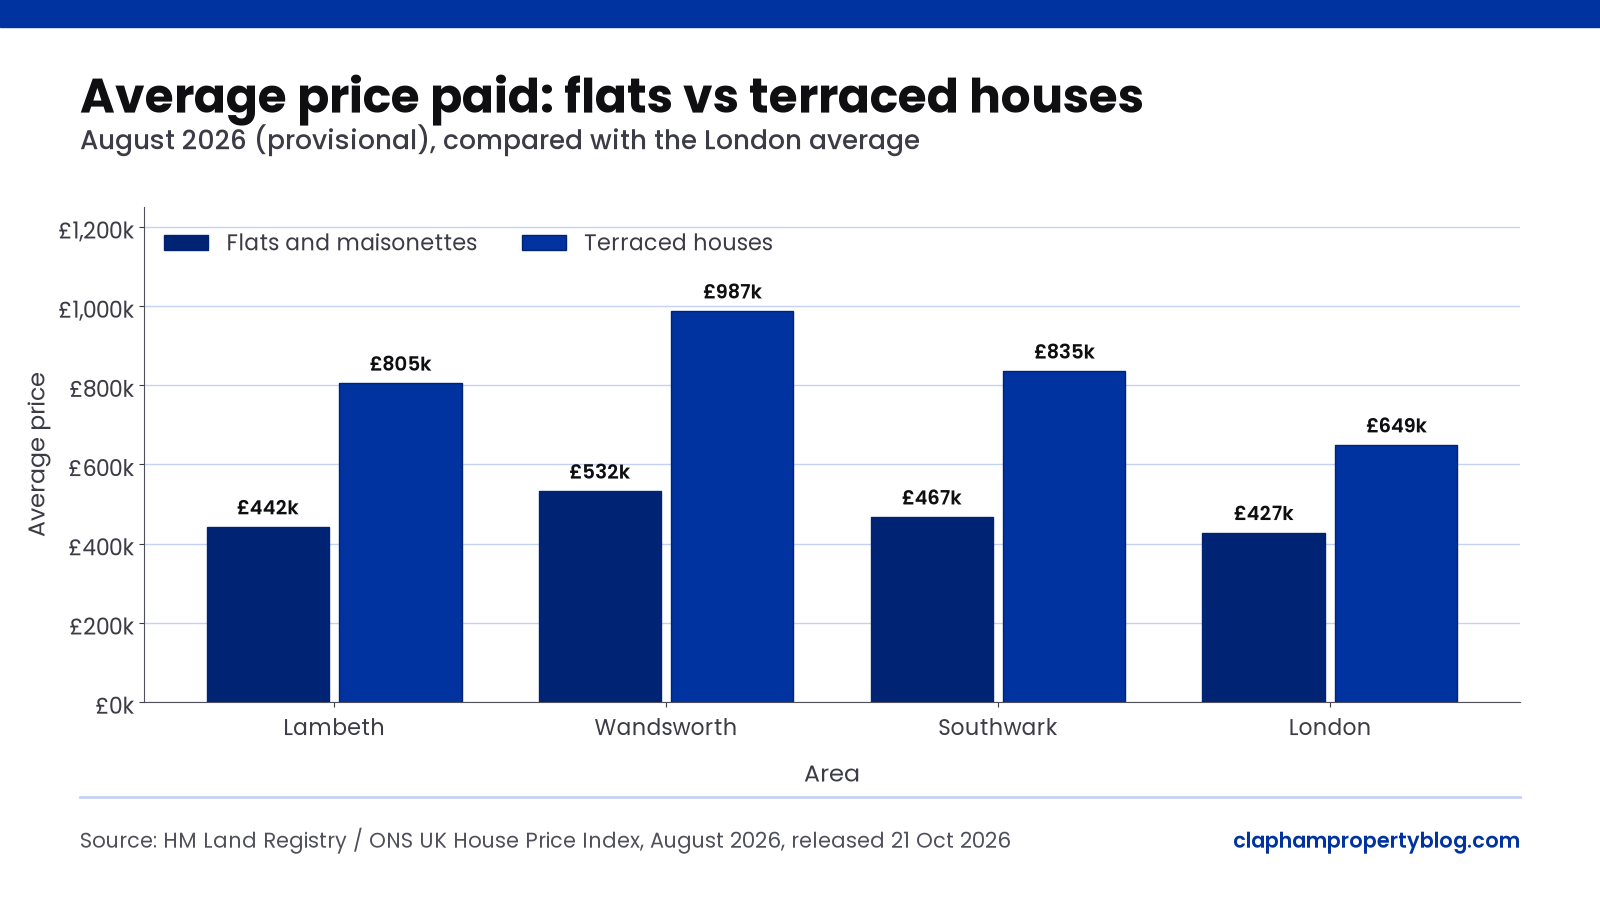
Average price paid for flats and terraced houses in Lambeth, Wandsworth, Southwark and London, August 2026

"What's a flat worth round here?" and "what should I be paying in rent?" are the two questions everyone in South London asks, usually over a drink and usually with a number they read somewhere that's two years out of date.

So let's use the official figures. On 21 October 2026 the ONS and HM Land Registry published the latest house prices (for August 2026) and private rents (for September 2026), borough by borough. Here's what they say for my patch.

One thing first. These are borough averages, not street prices. Lambeth covers most of Clapham, Brixton, Stockwell and Streatham. Wandsworth covers Battersea, Balham, Tooting and Wandsworth itself. Southwark covers Peckham, East Dulwich and Camberwell. A garden flat off Abbeville Road and an ex-local authority flat in Brixton sit in the same Lambeth average, and they're very different animals.

What is the average house price in Clapham and Brixton (Lambeth)?

£540,198 in August 2026, according to the UK House Price Index. That's down 6.5% on a year earlier, a steeper fall than London's 2.2%.

By type, Lambeth flats averaged £441,815 (down 7.2%) and terraced houses £804,615. First-time buyers paid an average of £474,320.

What is the average house price in Battersea and Balham (Wandsworth)?

£694,210, down 5.3% on the year. Wandsworth flats averaged £532,028 (down 6.5%) and terraced houses £986,873. First-time buyers paid £585,383 on average, the highest of the three boroughs.

What is the average house price in Peckham and East Dulwich (Southwark)?

£569,160, down just 2.1% on the year, in line with London. Flats averaged £466,671 (down 2.9%) and terraced houses £835,115. First-time buyers paid £497,815.

For comparison, the London average was £554,430, with flats at £427,310 and terraced houses at £648,650.

How much is rent in Clapham, Brixton, Battersea and Peckham?

ONS figures for September 2026 put the average private rent at:

  • Lambeth: £2,538 a month, up 3.4% on a year ago
  • Wandsworth: £2,640 a month, up 4.1%
  • Southwark: £2,516 a month, up 7.3%
  • London: £2,338 a month, up 3.5%

By bedrooms:

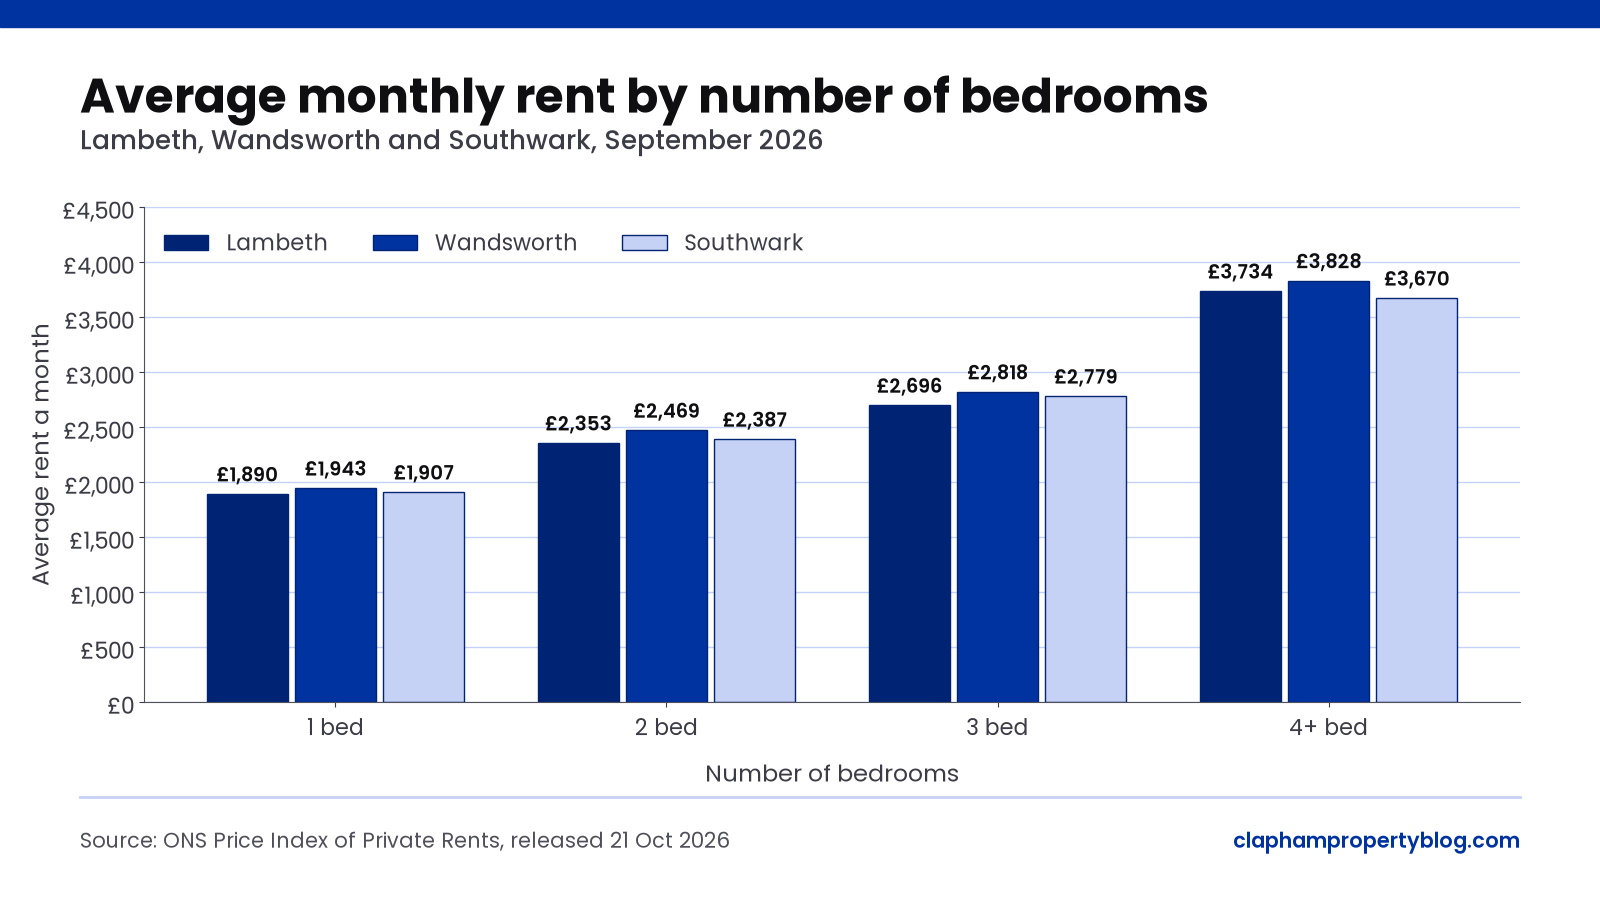
  • One bed: Lambeth £1,890, Wandsworth £1,943, Southwark £1,907
  • Two bed: Lambeth £2,353, Wandsworth £2,469, Southwark £2,387
  • Three bed: Lambeth £2,696, Wandsworth £2,818, Southwark £2,779
Average monthly rent by number of bedrooms in Lambeth, Wandsworth and Southwark, September 2026

So what does it mean for Clapham, Brixton and surrounds?

Now ears must perk up, because two things jump out.

First, rents and prices are going in opposite directions. Lambeth prices fell 6.5% in a year while Lambeth rents rose 3.4%. Southwark rents rose 7.3%, more than double the London rate. Generation Rent is still paying more, while the people who own the bricks and mortar have seen values slip.

Second, flats are taking the hit. In all three boroughs flats fell further than the overall average. I wrote recently about almost four in 10 London flats selling at a loss. This is the same story in the official numbers.

Who wins and who loses?

  • First-time buyers in Lambeth. The average first-time buyer price is down 6.7% in a year. If you've been saving for a flat in Brixton or Stockwell, that's real money off.
  • Flat owners looking to sell. With average flat prices down, pricing it right from day one matters more than ever.
  • Renters, especially in Peckham and East Dulwich. A 7.3% annual rise in Southwark is a big jump on top of already high rents, and sharers are feeling it too: room rents in inner London just hit £1,002.
  • Landlords. Falling prices plus rising rents means better yields for new buyers. Back of an envelope: Lambeth's average flat rent of £2,196 a month is £26,352 a year, about 6.0% gross on the average flat price. In Wandsworth (£2,341 against £532,028) it's about 5.3%, and in Southwark (£2,214 against £466,671) about 5.7%. Before costs, of course, and an average of all rents, not just new lets.

How much is my flat worth in SW4?

The honest answer is that a borough average won't tell you. Floor, outside space, lease length, condition and distance to the tube all move the number, and they can move it a lot.

The quickest way to get a real figure is a proper valuation. I'll come round, look at it, and tell you straight what it would sell or let for, with the comparables.

My take

Here's the thing. The headlines will say "London prices falling" and leave it there. Look closer and it's a flat market, not a house market, and a borough-by-borough market, not a London one. Wandsworth terraced houses still average nearly £1 million. Lambeth flats are down more than 7%.

If you're buying, this is the best negotiating position for years. If you're selling a flat, get the price right and get the presentation right. If you're a landlord, the yield maths is finally starting to work again.

So there you have it. A falling flat market, rising rents, and a lot of difference from one borough to the next.

Quick FAQ

Is it cheaper to rent in Brixton or Clapham? Both are in Lambeth, so the ONS averages don't separate them. Lambeth's average is £2,538 a month.

Which is cheapest to buy: Lambeth, Wandsworth or Southwark? Lambeth, at £540,198 on average in August 2026, then Southwark at £569,160 and Wandsworth at £694,210.

Are South London house prices falling? Yes, on the latest figures. Lambeth is down 6.5%, Wandsworth 5.3% and Southwark 2.1% year on year.

Where do these figures come from? The UK House Price Index (HM Land Registry and ONS) and the ONS Price Index of Private Rents, both published on 21 October 2026.

As always, are you thinking of buying, selling or letting in Clapham, Brixton, Battersea or Peckham and want to know what your place is really worth? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------
07837 093 554

Sources: HM Land Registry / ONS UK House Price Index, August 2026 (published 21 October 2026); ONS Price Index of Private Rents, September 2026, and ONS Housing prices in Lambeth, Wandsworth and Southwark (published 21 October 2026). Gross yield figures are my own calculation from those averages.

Saturday, 24 October 2026

Should you buy a modern flat now in Battersea?

Nobody wants flats. That's the line doing the rounds, and for once the numbers back it up. But here's the thing. When everyone runs one way, it's worth asking whether the bargain is going the other.

So what's happening?

The cold hard facts:

  • In June, Zoopla said over two-thirds of one and two-bed flats listed this year were still unsold. First-time buyers stepped back as borrowing costs rose.
  • Zoopla's September index has flats down 1.3% on the year, the only property type falling.
  • Closer to home, the official UK House Price Index puts the average Wandsworth flat at £532,028 in August, down 6.5% in a year.

Why? Leasehold, service charges and cladding. Nine years after Grenfell, the government is monitoring 4,724 buildings of 11 metres and over with unsafe cladding. Work hasn't started on 46% of them, and around 103,000 homes sit in those blocks. In Wandsworth, which covers Battersea and Nine Elms, between 101 and 200 buildings are on the list: 43% finished, 8% under way and 49% still waiting to start.

But what does it mean for Battersea?

Now ears must perk up. Battersea is modern flat country. Think of the riverside blocks, Nine Elms and the Power Station.

And it's not just numbers. Right now I'm seeing a lot of first-time buyers turning away from modern buildings, and that's leaving a lot of value on the table. That's my own observation on the patch, not a statistic.

The contrarian case, made recently by Property Hub (who run their own investor platform), goes like this. Cladding and leasehold problems are temporary. The flat is permanent. Buy while the price is down, and when rates ease the first-time buyers come back. Bear in mind that's a national view. Mine is local: Battersea, street by street.

There's something in it. Renters clearly like modern. Zero Deposit says build-to-rent homes in London average £2,560 a month against £2,280 for the wider market. Wandsworth private rents averaged £2,640 in September, up 4.1% in a year. And 89% of new homes get an A or B energy rating, while landlords face an EPC C standard by October 2030, with spend capped at £10,000 a property.

The catch

Let's face it, cheap can stay cheap.

  • Rates aren't easing yet. The Bank of England held Bank Rate at 3.75% in September, and three of the nine committee members voted for a rise. Next decision: 5 November.
  • Service charges. Concierge, gym and pool cost money. Ask for three years of accounts.
  • EWS1 and remediation. Has the building been assessed, who's paying, and when does work finish? Your lender will ask too.
  • Lease and ground rent. Check the years left and the ground rent.
  • Resale. If most flats listed this year haven't sold, plan for when it's your turn to sell.

My take

Buy the building, not the brochure. A modern Battersea flat with a long lease, a clean bill of health on the walls and a sensible service charge, bought at today's prices, looks like decent value to me. One with an open remediation question is a gamble, not a bargain. This isn't financial advice, so take independent advice, of course.

So there you have it. Unloved isn't the same as unwise. But in the flat market, the detail is everything.

Are you eyeing a flat in Battersea or Nine Elms, or sitting on one waiting for the market to turn? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

Sources: Zoopla press release (30 June 2026); Zoopla House Price Index, September 2026 (1 October 2026); HM Land Registry / ONS UK House Price Index, August 2026, and ONS Housing prices in Wandsworth (21 October 2026); MHCLG Building Safety Remediation monthly data release, August 2026 (30 September 2026); Zero Deposit build-to-rent research (June 2026); MHCLG Energy Performance of Buildings Certificates, April to June 2026 (30 July 2026); DESNZ private rented homes energy performance government response (January 2026); Bank of England Monetary Policy Summary (17 September 2026); Property Hub, "Nobody Is Buying These UK Properties (They're Buying This Instead)" (YouTube).

Uploaded Image

Friday, 23 October 2026

Autumn Budget countdown: four in 10 landlords say they'd raise rents if taxes rise - what it means for Clapham and Brixton

The Autumn Budget is almost upon us, and if you're a landlord you can probably feel your shoulders creeping up towards your ears already.

A new survey has put numbers on the mood. And, as usual, the people who'd feel the consequences most aren't the landlords at all. It's the renters.

So what's the survey saying?

LegalforLandlords asked 544 UK private landlords how they feel ahead of the Budget, which is due on 28 October. The cold hard facts:

  • 59% are pessimistic about the Budget.
  • Just 28% are confident that letting property will still be financially worthwhile in five years' time.
  • Capital Gains Tax is the biggest worry for 22%, income tax on rental income for 20%, and the cost of possible energy efficiency upgrades for 18%.
  • If the Chancellor raises the tax burden on landlords, 40% say they'd put rents up where they can. 18% would consider selling and 16% would leave the rented sector altogether.

To be fair to the researchers, they point out these are landlords' stated intentions, not a prediction of exactly what will happen. Still, it's a fairly clear message.

And bear in mind this isn't starting from a clean slate. As Property118 has reminded readers, last year's Budget already announced two percentage point increases in tax rates on property income from April 2027.

The Capital Gains Tax argument

Meanwhile the National Residential Landlords Association (NRLA) is lobbying for Capital Gains Tax reform in this Budget. Its argument is simple, and I have to say I agree with it.

At the moment, when you sell, the whole rise in value is treated as profit (apart from certain capital costs). The NRLA's research found that only around one-fifth of the rise in house prices between 2015 and 2024 was a real-terms gain - the rest was inflation. So it wants two changes:

  1. Tax the real gain, not inflation, by adjusting the purchase price and qualifying spending for inflation before working out the gain.
  2. Give relief for long-term holding, so someone who has housed tenants for years is treated differently from a short-term flipper.

As NRLA chief executive Ben Beadle put it: "It is absurd that investors face Capital Gains Tax on increases in property prices that are simply the result of inflation. That's not a real gain, and it shouldn't be treated as one."

The NRLA also points to Rightmove data showing each available rental property now attracts an average of 10 enquiries, double the pre-pandemic figure. Demand isn't the problem. Supply is.

So what does it mean for Clapham, Brixton and surrounds?

Now ears must perk up, because CGT is a very South London issue.

Picture a landlord who bought a flat off the Northcote Road or a two-bed conversion in Brixton 15 or 20 years ago. On paper, that's a big gain. In real terms, a good chunk of it is simply the pound being worth less. Under the current rules, the taxman doesn't care.

That landlord has three choices: sell and pay up, hold on and hope, or put the rent up to make the numbers work. The survey suggests a fair few will do the last one.

Who wins and who loses locally?

  • Renters in Clapham, Brixton and Streatham. If landlords' costs go up again, the survey suggests rents follow. With competition for every decent flat already fierce, renters have very little room to push back.
  • Long-standing landlords with big paper gains. CGT reform along the NRLA's lines would help them most. A tax rise would hit them hardest and could push some to sell up - which, of course, means one less rental home on the market.
  • Buyers. If more landlords sell, first-time buyers in places like Streatham and Tulse Hill could see a bit more choice. That's the silver lining, but it doesn't help the tenant who has to move out.
  • Newer, smaller landlords. Squeezed from both sides - higher tax on rental income from 2027 and rising compliance costs.

My take

Here's the thing. Every time the Treasury goes looking for money in the rented sector, the bill ends up on the tenant's doormat. It's not because landlords are greedy. It's because the sums have to add up, and if they don't, the flat gets sold.

The NRLA's CGT idea is sensible. Taxing inflation as if it were profit isn't fair, and it actively discourages landlords from staying in for the long term - which is exactly the kind of landlord renters want.

Will the Chancellor listen? I'm not holding my breath. My advice in the meantime: don't make a knee-jerk sale based on rumours. Run the numbers on your own portfolio, speak to your accountant, and wait to see what's actually announced. Take independent advice, of course.

So there you have it. A nervous few days for landlords, and potentially an expensive year for renters.

Are you a landlord in Clapham or Brixton weighing up whether to hold or sell before the Budget, or a renter worried about what comes next? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------

07837 093 554

Sources: LegalforLandlords survey via Property Reporter (16 October 2026) and Property Soup (19 October 2026), NRLA via Property Reporter (16 October 2026), Property118 (15 and 16 October 2026).

Uploaded Image

Thursday, 22 October 2026

Almost four in 10 London flats sell at a loss: what it means for flat owners and buyers in Clapham, Battersea and Brixton

Here's a headline to put you off your morning coffee. Almost four in 10 London flats that were resold after five to 10 years went for less than the owner paid for them.

Not a typo. Four in 10. And before the doom merchants get going, let's look at what the numbers actually say, and what they mean if you own, or want to buy, a flat South of the River.

So what's happening?

The figures come from e.surv Chartered Surveyors' October house price report, which compared repeat sales using HM Land Registry and Registers of Scotland data over the 12 months to August 2026.

The cold hard facts:

  • Across Great Britain, just over a quarter of flats resold after five to 10 years of ownership fetched less than their previous purchase price.
  • In London it was almost four in 10 - the highest proportion in the country.
  • Among London houses held for the same period, fewer than 4% sold at a loss.
  • Around a third of flats in the South East and East of England sold for less than they cost. In the Midlands and the North it was closer to one in five, and in Scotland fewer than one in 10.
  • Holding on longer didn't make the problem disappear. Across Great Britain, 16.6% of flats resold after 10 to 15 years fetched less than their previous price, against 1.9% of houses.

e.surv says flats and houses started to pull apart around 2017, as leasehold, building safety, cladding and service charges increasingly shaped the decisions of buyers, sellers and lenders. Interestingly, the gap is much narrower in Scotland, which has a different system for owning and managing flats. The report is careful to say that doesn't prove tenure is the cause, but it suggests the way flats are owned and managed may matter.

And the wider backdrop? The average home in Great Britain was £328,900 in September, down 0.2% on the month and the quarter, but still 1.5% up on a year earlier. London was the only region where prices fell over the year, down 2.3%.

If you want to feel even worse, a Telegraph analysis of Land Registry data put 76% of flats in England and Wales as loss-making in the 12 months to August once you allow for inflation. That's a real-terms figure, mind, not cash.

But what does it mean for Clapham, Battersea and Brixton?

Now ears must perk up, because our patch is flat country. Think of the converted Victorian terraces off Abbeville Road and Lavender Hill, the mansion blocks around Clapham Common, the ex-local authority flats in Stockwell and Brixton, and the newer glass towers along the river at Nine Elms and Battersea.

They are not all the same product, and buyers know it. Bear in mind what the report points to: leasehold terms, building safety and service charges. Those are exactly the things buyers and their lenders now pick apart on every flat purchase.

So, roughly speaking, here's who wins and who loses locally:

  • Sellers who bought a flat around 2016-2019. This is the group most likely to feel it. If you bought at or near the last peak and haven't added value since, a nominal loss is a real possibility.
  • Owners in blocks with cladding questions or chunky service charges. Expect buyers to ask harder questions and lenders to be choosier. Get your paperwork (lease length, service charge history, any fire safety documents) together before you list, not after an offer.
  • First-time buyers. Let's face it, this is good news for you. More choice, more room to negotiate, and sellers who are realistic about price. Do your homework on the lease and the building, though, because the reasons prices are soft are the same things that could bite you when you come to sell.
  • Landlords. A flat that hasn't grown in value can still earn its keep if the rent covers the costs. Yield and capital growth are two different questions.

My take

You see, here's the thing. A flat is not a bad investment because it's a flat. It's a bad investment when you overpay, buy a short lease, ignore the service charge or buy into a building with safety issues hanging over it.

The data tells me flat buyers have got wiser, and lenders more careful. Sellers need to catch up. Price it right, have the leasehold pack ready on day one and be honest about the building. The flats that are presented properly still sell. The ones that aren't sit there, and then the price comes down anyway.

Houses, meanwhile, keep doing what houses do in London. If you're a flat owner thinking about the next step up the ladder, the numbers are a reminder to look at the whole move, not just your sale price.

So there you have it. Not quite doom and gloom, but a clear message: in the flat market, the detail is everything.

Do you own a flat in Clapham, Battersea or Brixton and wonder where you stand, or are you a buyer weighing up a flat against a small house? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------

07837 093 554

Sources: e.surv Chartered Surveyors October 2026 house price report via Property118 (12 October 2026), The Negotiator (8 October 2026), The Telegraph (2 October 2026).

Uploaded Image

Tuesday, 20 October 2026

The landlord register isn't a one-off: the 28-day rule for landlords in Clapham, Brixton and surrounds

A Facebook post has been doing the rounds. It says the new landlord register is NOT a one-off form but a "live record", where every change - a new gas certificate, a rent rise, even your tenant's partner moving in - must be updated within 28 days or you face a fine of up to £7,000. And, of course, there's a handy checklist "in the comments".

Credit where it's due, the post is mostly right. But "mostly" is doing a lot of work there.

So what's actually happening?

The register comes from the Renters' Rights Act 2025, with the detail in the draft PRS Database Regulations 2026, laid before Parliament on 9 September. Two things the post leaves out:

  • The regulations are still a draft. Both Houses have to approve them before they're made.
  • The penalties aren't in force. They need a separate commencement order, which hadn't been made when I checked.

Nobody in SW4 is getting fined next week.

The 28-day rule

Under the draft regulations, when any information or document on your landlord or property entry "becomes out of date", you have 28 days to update it. Registering isn't fire and forget.

What's on the record for each property:

  • the number of occupants and households
  • HMO, additional or selective licence status and numbers
  • the gas safety record, EICR and EPC
  • the rent, how often it's paid and which bills are included
  • whether it's furnished, and whether it's currently let

So yes, a partner moving in changes the occupant count, and the NRLA reads renewed certificates and rent changes as updates too. (The draft regulations don't list trigger events, and official GOV.UK guidance isn't out yet.)

But "every change"? No. Tenant names, deposits and repairs aren't on the list. Fixing the boiler isn't a register event in itself.

It's annual too

Entries must be renewed every 12 months. GOV.UK puts the fee at £65 per property per year, though it can change. And if you have more than one property, they all share the renewal date of your first one.

Quick numbercrunch for a landlord with three flats: 3 x £65 = £195 a year, all due on the same day. Put it in the diary.

What the penalties really are

  • Up to £7,000 for failing to register or keep entries up to date. That's a maximum. Each council sets the amount, and there's no minimum.
  • Up to £40,000, or prosecution, for knowingly or recklessly giving false information, carrying on more than 28 days after a penalty is final, or another breach within five years of a penalty.
  • No rent repayment order just for being unregistered. An RRO only comes into play for the false-information offence, or for carrying on after a penalty.
  • No possession order without an active entry. Apart from two anti-social behaviour grounds, a court can't make a possession order while you have no active landlord or property entry. An entry you didn't renew counts as inactive, and so does one where the tenancy and safety details weren't added within 28 days.

A correction from me

In my last post on the register I said the penalty for ignoring it could be two years' rent. That overstated it. Simply not registering means a penalty of up to £7,000 and a block on possession, not a rent repayment order. I also said tenants will be able to check whether their landlord is registered. That's the plan, but not at launch - public access needs further legislation and there's no date yet. I'd rather tell you straight.

But what does it mean for Clapham, Brixton and surrounds?

London is the second-last region. Duties start on 15 July 2027 and the deadline is 14 October 2027, for Lambeth, Wandsworth and Southwark alike. So Streatham, Brixton, Battersea and most of Dulwich all register in the same window. It depends on where the property is, not where you live.

Picture an accidental landlord with one flat off Abbeville Road. She registers in August 2027 and forgets about it. Next spring her tenant's partner moves in and the rent goes up. On the NRLA's reading that's two updates, each with its own 28-day clock. Then, in August 2028, the renewal.

A letting agent can update the tenancy and safety details and whether the property is let. What they can't do is register you in the first place. That's on you.

Who wins? Organised landlords with one folder per property. Who loses? The shoebox brigade.

About that checklist in the comments

I'm not calling any particular post a scam. But "link in the comments" is a classic engagement-bait trick, and those links are sometimes lead-capture forms, paid "compliance packs" or pages dressed up to look like GOV.UK. Register only through the official GOV.UK service (or its official paper form), where the only fee mentioned is £65 per property. Don't pay a third party to "register" you, and be suspicious of any unsolicited "register now" message before the service opens on 15 December 2026.

My take

The post is broadly right, just early and breathless. Good landlords already know when their gas certificate is due. The real risk in Clapham and Battersea isn't a £7,000 fine landing on the doormat. It's a stale entry quietly going inactive just when you need possession.

In summary

So there you have it. A 28-day update duty for the listed items, an annual £65 renewal on one shared date, and penalties not switched on yet. London's window is 15 July to 14 October 2027.

Are you a landlord in Clapham, Brixton or Dulwich, and have you got a system for keeping your paperwork current? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------

07837 093 554

Sources: Draft PRS Database Regulations 2026 and Explanatory Memorandum (legislation.gov.uk), Renters' Rights Act 2025, GOV.UK Housing Hub, GOV.UK civil penalties guidance, NRLA.

Uploaded Image

Saturday, 17 October 2026

The landlord register opens in December: what landlords in Clapham, Brixton and Streatham need to do now

For the first time ever, England is going to keep a single list of who lets property and where. Scotland, Wales and Northern Ireland have had one for years. Now it's our turn, and it comes with a fee, a deadline and a lot of paperwork.

So what's happening?

The new Private Rented Sector Database, better known as the landlord register, opens in the West Midlands on 15 December 2026. Other English regions follow in stages until August 2027, according to Property Reporter (16 October). Landlords will have three months to register once their region opens, and the fee is £65 a year per property.

To register, you'll need each property's gas safety record, electrical safety report and EPC. Property Reporter's guest piece from Logan Ransley of Landlord Studio (12 October) makes the point that this is where many landlords will discover something missing or out of date. That gas certificate buried in an old email. The electrical report that quietly expired last spring.

And there's teeth. Tenants will be able to check whether their landlord is registered, and once the rules are fully in force a tenant renting from an unregistered landlord can apply to get back up to 24 months' rent. Two years' rent. That should focus a few minds.

Councils are also being funded to enforce the Renters' Rights Act. Ransley's FOI request found Newham's funding more than doubled in a year, from around £169,000 in 2025/26 to more than £364,000 in 2026/27, even though Newham landlords won't have to register until next summer.

It all lands in a busy year. Making Tax Digital started in April for landlords with qualifying income over £50,000, most of the Renters' Rights Act came into force in May, and Property Reporter (12 October) noted only 35% of landlords can name their own MTD start date. TwentyCi found around 560 rental properties a day were sold in Q3 2026, up from around 500 a day a year earlier and fewer than 170 in 2020.

But what does it mean for Clapham, Brixton and surrounds?

Our patch straddles Lambeth, Wandsworth and Southwark, with Streatham and Brixton in Lambeth, Battersea in Wandsworth and Dulwich mostly in Southwark. If Newham's "next summer" is a guide, London landlords probably have a few months yet. Registration for Lambeth, Wandsworth and Southwark landlords is expected in 2027.

Bear in mind that your deadline depends on where the property is, not where you live. If you live in Dulwich but own a flat in Birmingham, you could be registering that one first, from 15 December.

Think about who lets in our area. Accidental landlords who kept a flat in Clapham Old Town when they moved out to start a family. Long-term investors with a few conversions off Streatham Hill. Owners of new-build flats around Battersea Power Station. The professional, fully managed landlord will barely notice. It's the one-flat, do-it-yourself landlord who is most likely to be caught out.

Quick numbercrunch for a landlord with three flats:

  • Registration: 3 x £65 = £195 a year
  • Risk of not registering: up to 24 months' rent per tenancy

Not a hard choice.

Who wins and who loses?

  • Good landlords. Mostly fine. As Dirk Dette of Campions Group put it via Property Reporter, the information requested largely relates to obligations landlords should already be meeting. The difference is that gaps become visible.
  • Disorganised landlords. Expired certificates and missing paperwork will show up quickly.
  • Rogue landlords. That's the theory, anyway. Veco's chief executive Richard Murray asks the obvious question: will those determined to operate outside the rules simply choose not to register?
  • Tenants. A public way to check their landlord is legitimate, and a powerful remedy if not.

My take

I'll be honest, I share Veco's scepticism. The compliant majority will dutifully pay their £65 and upload their certificates, while the cowboys at the bottom of the market carry on as before unless councils have the people and the will to chase them. The Newham funding figures suggest the money is starting to arrive. Whether that becomes enforcement on the ground in Lambeth and Wandsworth is another matter.

That said, I'm not going to pretend this is a disaster. Another layer of admin, yes. Another £65 per property, yes. But for good landlords it's a chance to prove they do things properly, and in a market where tenants have more choice than ever, being visibly compliant could become part of what you're selling.

Practical steps for now, borrowing Ransley's three-step plan: check which region each of your properties sits in; pull all certificates, expiry dates and tenancy agreements into one place per property; and start logging rent, costs and tenant messages as they happen rather than at year end. An hour a month beats a lost week when the council or HMRC comes knocking.

In summary

So there you have it. The register opens on 15 December, costs £65 a year per property, and the penalty for ignoring it could be two years' rent. London's turn looks like 2027, but the paperwork you'll need is paperwork you should already have.

Are you a landlord in Clapham, Brixton or Streatham, and is your certificate folder in order, or more of a shoebox? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.

---------

07837 093 554

Sources: Property Reporter (12 and 16 October 2026), Landlord Studio, Veco, Campions Group, TwentyCi.

Uploaded Image

Friday, 9 October 2026

Room rents in inner London just hit £1,002: what it means for sharers in Clapham


Spend ten minutes on the Common on a Saturday and you'll spot them: two or three mates, coffees in hand, walking back from a viewing they've just queued for. Flatshares are the engine room of Clapham. They always have been. And this week the numbers caught up with what I've been seeing on the ground all autumn.

Room rents in inner London have reached an average of £1,002 a month. That's up 2.3% on the quarter and 1.1% on a year ago, and it's within a pound of the all-time record of £1,003 set at the end of 2023 (figures reported this week via SpareRoom). Nationally, the average UK room now costs £769 a month, itself a fresh record, up 1% on the year. So renting a single room in a shared flat down here now costs more than renting a whole one-bed does in large parts of the country.

It isn't a blip either. Surveyors expect more of the same: a net 37% of them told RICS they think rents will keep rising over the next three months. Demand is up, supply is down, and nothing in the pipeline suggests that flips soon.

For a young professional moving to Clapham, Balham or Stockwell, the sum is sobering. A £1,002 room is roughly £12,000 a year before a single bill, before council tax, before the Northern line. Share a three-bed off Abbeville Road or near Clapham Common and the landlord is collecting around £3,000 a month for the flat. That's why so many sharers I speak to are staying put rather than moving in the autumn. The devil you know is cheaper than the devil advertised on the portal.

For landlords, it looks like a win, and in cash terms it is. But I'd read it with a cool head. Rents at or near record highs are not a sign of a healthy market. They're a sign of a market that has run out of homes. Tenant demand keeps climbing while rental stock keeps shrinking, and squeezing more out of a smaller pool is not a strategy, it's a symptom. When affordability stretches this far, you get more arrears, more churn and more tenants who simply can't take the next increase.

Here's my take. If you're a sharer in SW London, the smart move right now is to lock in. A good flat with decent flatmates at a fair rent is worth holding through the winter rather than rolling the dice in a market where every viewing has a queue behind you. Talk to your landlord about a longer term before your renewal lands, because stability cuts both ways and most will take a reliable tenant over a void. And if you're a landlord sitting on a flat that works, resist the temptation to chase the headline number to the last pound. The best tenants are the ones who stay, and in this market keeping a good one is worth more than a £50 bump that pushes them out the door.

Are you sharing in Clapham and feeling the squeeze, or a landlord weighing up a renewal this winter? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.


---------

07837 093 554

Saturday, 19 September 2026

The £65 landlord register is here - what every Clapham landlord needs to do now

I had a call this week from a landlord who owns one flat near Clapham Common - a flat she used to live in, now let to a lovely couple. She isn't a property mogul. She's an accidental landlord with a single tenancy and a full-time job. And she wanted to know if "this new register thing" applied to her. It does. So if that sounds like you, read on.

The government has now launched the private rental registration service and confirmed the timetable for the mandatory database of landlords and rented properties in England. The headline figure is a £65 annual fee - per property, not per landlord - to register. Alongside it, HMRC is being lined up to handle rent-increase disputes, which is a real shift: the argument about whether your rent rise is fair moves into a formal channel rather than a conversation on the doorstep. This is all part of the machinery of the Renters' Rights Act finally being switched on.

Here is what the register actually is, in plain English. It's a national record of who lets property and which properties are let, tied to your compliance paperwork. Think of it as an MOT logbook for the rental sector. You register the landlord, you register each property, you pay the fee, and you keep the details current. It is not optional and it is not something you can quietly ignore, because it plugs into the wider enforcement regime - the same one where licensing breaches under the Act can now carry fines of up to £40,000.

clapham-blog-landlord-register-65-2026-09-12.jpg

For a Clapham or Balham landlord, the practical to-do list is short but real. First, get your compliance file in order before you register, not after - gas safety certificate, EPC, electrical safety report and deposit protection details. Registering with gaps in that paperwork just paints a target on your back. Second, budget for the fee across your portfolio: £65 on one flat is nothing, but if you hold four or five conversions around Abbeville Road or Stockwell it adds up and it recurs every year. Third, get your head around the rent-review process now, because with HMRC in the mix the days of an informal "I'm putting it up £150" are over. Do it properly, in writing, on the right form, at the right time.

My take? This is more admin, and no landlord enjoys more admin. But I'd resist the urge to see it purely as a burden. A register that pushes the worst operators out - the ones letting damp, unsafe flats and dragging the whole sector's reputation down - is no bad thing for the good landlords who already do it right. If you keep a decent flat, look after your tenants and hold your paperwork properly, this changes very little about how you operate. It just writes down what you were already doing. The landlords who should be nervous are the ones who've been cutting corners, and frankly, in a market as scrutinised as SW London, those days were numbered anyway.

The one thing I'd say clearly: don't leave it. Registration and the new rules are being rolled out on a fixed timetable, and the landlords who scramble at the deadline are the ones who make expensive mistakes.

Are you a landlord in Clapham or the surrounding area wondering how the register affects your flat? I'm happy to talk it through - drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.


Virus-free.www.avast.com

Monday, 14 September 2026

London rents just jumped 9.8% in a month. Here's what's really going on in Clapham

Stand outside any letting board on Clapham High Street for ten minutes and you'll see it: a viewing, then another, then a couple already filling in a holding form on their phone before they've left the pavement. The queue is real. And this week the numbers caught up with what we've been living down here all summer.

Advertised rents across London rose 9.8% in August. That is not a typo, and it is not annual growth dressed up as a monthly figure - that is where asking rents landed last month as landlords listed higher. At the same time, flatshare supply fell 3.2% and room rents hit a fresh record high. Fewer rooms, fewer flats, more people chasing them. Nationally, gross rent on the average landlord's portfolio has climbed to somewhere between £88,454 and £90,000 a year, and rental growth is now accelerating across five English regions since the Renters' Rights Act landed.

So what is actually driving it? Part of it is the Act itself. With Section 21 gone and rent reviews tightened, a lot of landlords are front-loading: if you can only realistically move the rent once a year through a formal process, you set it higher at the start. That is not greed, it is arithmetic, and it is showing up in the asking prices from Stockwell to Streatham. The other part is plain supply. Every landlord who has sold up over the last two years, spooked by tax and regulation, is a flat that has left the rental pool for good. Down here, where two-bed conversions off Abbeville Road and around Clapham Common are the backbone of the market, that thinning stock bites hard.

If you're renting in SW London right now, the honest advice is to move fast and come prepared. Have your references, deposit and proof of income ready before you view, not after. A well-presented flat near the Common at a fair rent is gone in days, and the person who gets it is usually the one who could say yes on the spot. Stretching your budget by £100 a month to widen your search into Tooting or Balham will often get you far more than holding out for a bargain that isn't coming.


image.png


If you're a landlord, this is the moment to be careful, not cocky. A record asking rent means nothing if the flat sits empty for three weeks or the tenant leaves in six months because the price never stacked up. Voids are the quiet killer here - four in ten portfolios nationally are carrying them - and an empty month wipes out most of the gain from a punchy headline rent. Price it to let quickly to a good tenant who stays, and you'll almost always beat the landlord chasing the top of the market.

My take: this is a supply problem wearing a price-rise costume. Rents aren't high because tenants suddenly have more money - they're high because there isn't enough to go round. Until we get more homes into the SW London rental market, not fewer, this pressure isn't easing. And every well-intentioned rule that nudges another landlord towards selling makes it a little worse for the renters it was meant to help.

Are you feeling the squeeze on the rental market in Clapham - as a tenant or a landlord? I'd genuinely like to hear how it's playing out on your street. Drop me a line at jeroen@claphampropertyblog.com or call 07837 093554.


Virus-free.www.avast.com

London asking rents are up 7.6%, but deals are being done 4.4% below: how renters and landlords in Clapham, Brixton and Streatham should play it

Read the headline and you'd think London rents were running away again. Read the small print and there's a very different story. Wh...

Popular Post!