Showing posts with label capital growth. Show all posts

Monday, 24 July 2017

Video Series 6/30 - How chicken shops can help you identify a great investment area!

So what do chicken shops have to do with the price of fish??

Find out more in this video:


If you like this video please like, comment and share and join the Clapham Property Blog community on Facebook, LinkedIn and Youtube. If you prefer old fashioned email just drop me a line or come and meet me in person at the Clapham Property Meet!

Monday, 22 August 2016

More contradicting headlines in the news today. What's really going on in Clapham?

Not a day goes by that I don't have my finger firmly on the pulse. Be it Clapham, Brixton or beyond I do like to get a feel of what is going on in South London. As do you, I'm sure.

Today, however, I was confronted with such contradicting headlines I couldn't help but tell you about it.

A selection:
House price growth to slump 1% post-Brexit
Prime London prices cool in Q2
Limited company applications surge in June
43 million Brits 'would go over budget' for the right home


The first claim about house prices "slumping" (if you can call 1% a slump) was made by Fionnuala Earley, Countrywide’s Chief Economist. Forgive me for not immediately agreeing. Countrywide have not exactly been the best bunch of business people or estate agents for that matter, so much so that they are now investing heavily in online property sales. Anyway, rest assured, they do conclude with something sensible such as "Countrywide says they will mean prices returning to levels similar to Q1 2016". Scaremongering over.

The second article again has a misleading title. You get the jist of the article by the title you would have thought, but I quote "The rate of quarterly house price growth in Prime London cooled in the second quarter of the year, with a 0.3% decrease from the opening three months of the year". Yes, you read that right, the RATE OF HOUSE PRICE GROWTH. So there is still growth. Excellent news.

On the brighter side you will see that limited company applications are up in the mortgage sector. A very interesting development - it is clear that astute landlords have taken advice to proceed down such a route. Thanks to a growing number of lending products now available to limited companies (this has grown exponentially over the course of this year) more and more landlords are incorporating and taking advantage of this tax efficient way of holding a portfolio. A clear sign that a) opportunities are there and b) investors are not holding back.

The last headline pertains somewhat to investors using a "buy-to-sell" strategy. Excellent news really. In a nutshell 75% of people would stretch the budget to get the ideal property that suits their needs. With this in mind I re-emphasise that knowing your target audience can pay dividends. A bidding war worth of dividends, mind you! A recent development of mine saw a bidding war - perhaps due to the modern bathroom with underfloor heating, perhaps because of the wine cooler in the kitchen. Maybe both. I know for a fact though that first time buyers like aspirational property, so sell that lifestyle; the key to a successful development.

In summary, read closely. Headlines conflict, but the overall message is still clear: there is a market for your product (property). If you are selling, ensure you know your audience. Same goes of course for your letting portfolio, but key is to structure wisely to minimise your tax bill. With recent changes you will see some of your tax breaks go, so make sure you adapt, or you will lose money to the Chancellor of the Exchequer.

To finish off, a lovely quote from the first article: "Annually, Prime London prices saw a 1.3% increase, rising to 2.7% in Outer Prime London. This has been driven by particularly strong growth in certain south London areas, with Clapham (9.2%) and Balham (6.5%) – forever popular with aspirant, young professionals – leading the charge. North Kensington (5.1%) also enjoyed solid price growth on a year-on-year basis." Lovely news of course, so let's keep investing locally!

Remember - if you are after investment advice, whether you are looking to grow your existing portfolio or start afresh then do get in touch by emailing me on jeroen@claphampropertyblog.com or come and meet me at the Clapham Property Meet Wednesday 28th September. There are still a few tickets remaining to the event, so do RSVP promptly here. Also, if you are looking for hands-off investing and you wish to invest upwards of £50,000 then do get in touch as I have a number of transactions that are ready for funding within the next 2-12 weeks. I help investors like you make better returns on their investment. I have done so for nearly 15 years, with proven results. If you are interested in taking the next step on your investment journey then reach out and I will expertly guide you through the process. I am actively looking for clients to invest with and for to expand the current successful portfolio. 

Wednesday, 25 November 2015

Where should I buy my next property? Brixton or Clapham? How many bedrooms? House or flat?

So, another profitable year draws to a close. We all know that very little happens in the property market in these last few months of the year, so now is probably a good time to recap on what’s happened locally. It’s also a brilliant time to set your goals for 2016. How many properties are you planning on buying? Refinancing? Refurbishing? Adding value to?

Let’s look at some numbers I’ve compiled, courtesy of Zoopla. My main aim is to point out areas of good growth for you, the investor.


Brixton SW2
Clapham SW4
Average Value
£496,886 up 5.22%
£843,777 up 6.74% (12m)
Flats
£405,081 up 4.96%
£566,979 up 5.36% (12m)
Terraced
£738,939 up 7.41%
£1,344,463 up 7.95% (12m)
Semi D
£914,410 up 0.66%
£1,808,612 up 0.66% (12m)
Average Rent
£1,822pcm
£2,141pcm
Average gross yield
4.4%
3%
Number of transactions
542
445

This table certainly makes interesting reading. On the face of it you’d be inclined to buy in Clapham straight away (average values up), but there are certainly advantages to both areas. For one, you can see that the average gross yield in Brixton is nearly 50% more than in Clapham! So rents are much greater in relation to the purchase price. That’s a good thing, because that will make up for the slightly slower house price growth we’ve seen compared to Clapham over the last 12 months. Also interesting to note is that terraced houses are absolutely unaffordable as a buy-to-let, with vastly diminishing yields, only made good by the increase in capital value.

Should I buy in Brixton or Clapham?
Well that depends. Historically we can see that both are good bets. But decide what you are going for: capital appreciation, on the face of it, looks stronger in Clapham but rental yields are definitely better in Brixton. But let’s compare over a longer period. Queue a beautiful graph again courtesy of Zoopla. Now look at how SW2 prices are keeping pace with SW4. There is a difference. But the gap isn’t widening. So as far as investment goes I think Brixton has more to offer in terms of house price growth as gentrification increases and “Brixton Villaaaage” becomes even more popular.


So we’ve decided that Brixton has the best yields and best potential based on historic data and trends. Which property is doing well? 1beds? 2beds? No, it’s actually 3beds which are doing the best. They are still relatively affordable (a big word in London of course) and command the best rents as a percentage of purchase price. Also personal experience tells me that they are ALWAYS in good demand.
   
SW2

1 bed
2 beds
3 beds
4 beds
5 beds
Houses
Value
£385,000
£517,492
£705,702
£1,073,638
£1,238,325
Rent
£901
£1,807
£2,440
£2,977
£3,398
Yield
2.81%
4.19%
4.15%
3.33%
3.29%
Flats
Value
£372,569
£512,683
£595,585
£514,544
-
Rent
£1,280
£1,652
£2,970
£2,743
Yield
4.12%
3.87%
5.98%
6.40%

All
Value
£372,958
£513,387
£635,820
£929,871
£1,238,325
Rent
£1,263
£1,661
£2,872
£2,919
£3,398
Yield
4.06%
3.88%
5.42%
3.77%
3.29%


SW4

1 bed
2 beds
3 beds
4 beds
5 beds
Houses
Value
£499,950
£873,000
£879,988
£1,456,663
£2,506,250

Rent
£1,077
£2,136
£3,656
£4,444
£4,695

Yield
2.59%
2.94%
4.99%
3.66%
2.25%
Flats
Value
£508,714
£702,250
£762,349
£1,071,000


Rent
£1,581
£1,970
£2,321
£3,049


Yield
3.73%
3.37%
3.65%
3.42%

All
Value
£508,412
£713,195
£787,115
£1,360,248
£2,506,250
Rent
£1,564
£1,978
£2,714
£3,921
£4,695

Yield
3.69%
3.33%
4.14%
3.46%
2.25%


Interesting to see that 3 bed flats are offering a near 6% yield in Brixton. Tell me it isn’t so, my chants in April of three bed flats in SW2 being a good bet were fairly accurate.


So if you want more advice on what to buy, where to buy it and when – just drop me a line on jeroen@claphampropertyblog.com. Helping landlords make wise investments now and in 2016. 

Friday, 22 May 2015

Property values up in Clapham up by 18% and Brixton by 20%

A landlord came in to seem me the other day and he was keen to hear more on my take on the market. He had been investing in established areas such as Kensington and Chelsea for years and had made a lot of money in doing so. He was telling me that over the years he had made great investments in SW3 but was curious to hear more about the property market South of the River Thames, particularly Clapham and Brixton.

I was all too glad to oblige. I've seen a lot over the years. Clapham and Brixton have changed. For better, in the property sense. What I've seen over time is that Clapham has been Brixton’s affluent neighbour. This is still true to a certain extent; property prices are indeed higher there. Indeed places like Clapham Old Town and Between The Commons (arguably Battersea but we’ll agree it’s a desirable area bordering Clapham Common so let’s call it Clapham today) have always been desirable and you will see a lot of families living here. Less flats, more houses. And these prices, just like properties in Chelsea have gone up a good amount over the years.


What’s the problem then? Buy the most expensive house you can afford in the nicest possible area and you will have the best investment? Yes and no. Maybe a great investment from a capital growth perspective. Not the best investment from a yield perspective. You see here’s the thing. The desirability of those houses is very much restricted to a certain target audience – families. And as you will know from various research people are waiting longer and longer to start families. Single occupation units are on the rise. Why do you think all these room let people are doing so well? So let’s look at Brixton for instance. Hip, young trendy, the Dalston of 2014 it was called. Or Hoxton or Deptford, I can’t keep up with this skinny drainpipe jeans bearded lot… Anyway point I’m making is that properties are CHEAPER to buy in Brixton than they are in Chelsea. And more desirable for the hip and trendy young folk. Which is good, because they want to rent. They don’t want to be tied down with a wife, kids and a labracockadoodledoo (or whatever). This means that rental demand is better – it always is in cheaper segments of the market. Cheaper cars sell in greater volume than Bentleys and Rollers…Families don't want to rent as much, so your expensive house won't yield as well as a smaller house or flat in Brixton for example. With yield I mean the % of rent vs purchase price.


Now Mr. Landlord reminded me that his property’s prices went up by 17.8% in the last two years. I reminded him that SW4 property prices went up by 18.4% over that period and SW2 property prices went up by 20%. And with better rental yields than in Chelsea he had seen the light. He quickly asked me to source some investments for him!


If you’re ever passing by Clapham Park Road or you fancy a chin wag about the weather or property (I know a bit more about the latter truth be told) come in and see me! Or drop me a line on jeroen@xandermatthew.com or hop on the phone 020 3397 2099. Happy to talk investments and property all day long.

Thursday, 21 May 2015

Make a 2bed a 3bed? A 3bed a 4bed? Wow that will increase your rent!

I was approached by one of my more savvy buy-to-let investors the other day and asked me if he could make a quick buck by turning a 3bed into a 4bed. You're probably thinking "no, not really, it costs money to build an extension" and so forth. This is true. However he had spotted an opportunity that not a lot of investors make use of, and if they often do it they do so badly and "compromise" the property.

I thought I'd say a few words on the matter because for those of you who are new to the investing game - welcome - you may not know this has been happening for a long time. Let me explain.

As London gets more and more expensive developers and end users are looking for more bedrooms and more space. More bedrooms tends to mean a property is more valuable. Now this isn't a license to take a carving knife to a floorplan and make the rooms only big enough for a single bed and floor space to put your slippers at night. There is of course a limit to how far you can go. But this limit has changed over time.

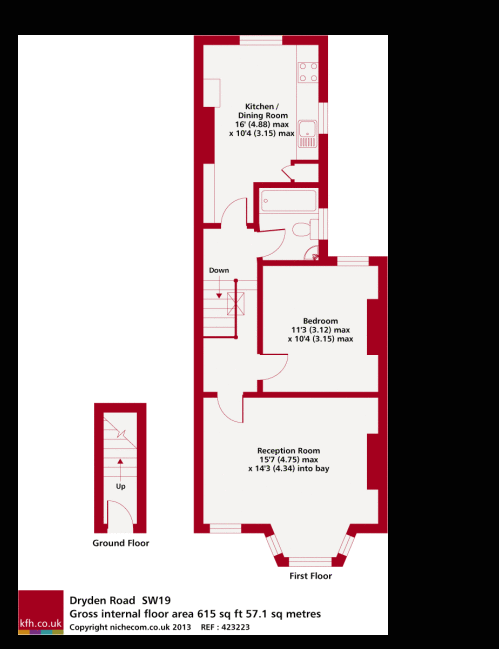
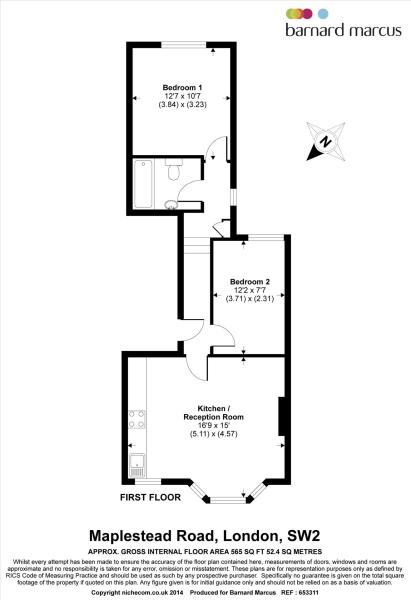
I'll take three examples, one purpose-built flat and two Victorian conversions to show you what is possible with very little investment. Perhaps moving a kitchen and putting up a stud wall. Ground floors often cost a little more though as they involve an extension.

so: example 1: a typical Victorian conversion on the first floor:
Floorplan 1Floorplan 1

See what was done there? move the kitchen into the living room and VOILA - a 2bed. You'll notice the one on the right goes in a bit at the side, that's only because there's another flat on top, Proving the point even more - the developer even converted the loft into a separate flat. Another good angle!


Example 2: You can actually do this with a bit more work to a ground floor flat but that involves an extension. I've included 2 "after shots" because one is particularly better than the other, the last one has a side return filled in which gives even more space (and it's silly not to do it really, minimal cost).


See what was done here? Extension at the back becomes open plan kitchen/living and the bedrooms are at the front. (I've flipped the one on the left up-side down so it's easier to see the changes.)

So what about purpose-built flats? You can hardly extend a purpose-built block can you (well believe me when I say I've seen it done, don't ask re consents!!)?!?

Here is "le grand truc:"
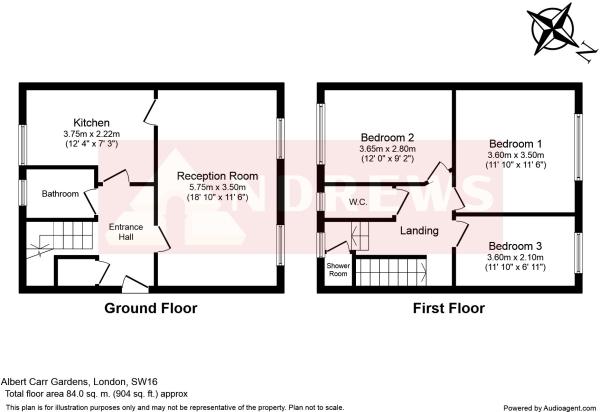
A typical 3bed maisonette:
albert carr gardens


Move a stud wall here and there and VOILA! a 4bed! Excuse my crude paint job...


So there we have it, I hope that's been interesting. But to come back to the original point - does it add value? Yes and no is the answer. You will get more rent, that's for sure; you will get a better sale price, that's for sure. But within reason. If the flat is too small to start with there is no hope - it still needs "reasonably sized" rooms. Now "reasonable" changes over time, reasonable becomes smaller as gentrification takes hold. Whereas years gone by 500sqft was acceptable for a 1bed it is now not uncommon to see 2beds with that square footage. All of the examples I used are fairly run of the mill, there are much more creative and compromising ones out there. Adding value can be done best my maximising space, and then you are talking loft conversions or filling in side returns. If you just move stud walls around you will get a return on your investment that's for sure (more rooms means more rent), but unless the place is a wreck and you're adding value anyway by refurbishing it there is little scope for a profit in the short term. Those work best as hold and rent investments because you will be able to remortgage and release capital in 2 years or whenever your mortgage deal comes to an end.

And PS there are a few examples around of people making the most of an extra bedroom:
here's a flat in a block which is being sold as a 2bed:

and this one in the same estate is being sold as a 2bed but I have a sneaking suspicion that it was a 1bed before, the council didn't build open-plan kitchens back in the day!
A 1bed in that block sold for 266k (no internal photos so presumably a wreck) http://www.rightmove.co.uk/house-prices/detailMatching.html?prop=24800750&sale=53566832&country=england - perhaps it's the same one? No way to tell, really, but not unlikely!

So if you are prepared to spend 30k doing it up that makes a tidy profit!

So you can see first hand examples of someone buying a 1bed, turning it into a 2bed and charging a premium for their work. Which I endorse of course because it's entrepreneurial! I'd do the same quite frankly. In this example 266 plus perhaps 30-40k in costs means a yield of around 6%, so it could do well as a hold and rent if it's not sold around 350-360k to give a short term profit of 50-60k. Brilliant strategy, brilliant exit plan - doesn't sell? Let.

I'm off to find the next deal.

If you fancy talking property give me a call on 020 3397 2099 for a chat or drop me a line on: jeroen@xandermatthew.com – I'm always on hand to answer any property related questions.


* Naturally I don't want to infringe copyrights and the such, the floor plans used in this article are freely available online and I don't want to pass them off on my own. All the relevant owners' markings have therefore been left on there as not to allow anyone to think otherwise.

Room rents in inner London just hit £1,002: what it means for sharers in Clapham

Spend ten minutes on the Common on a Saturday and you'll spot them: two or three mates, coffees in hand, walking back from a viewing th...

Popular Post!