Showing posts with label taxation. Show all posts

Thursday, 10 August 2023

South London Homeowners Bracing for ULEZ Attack

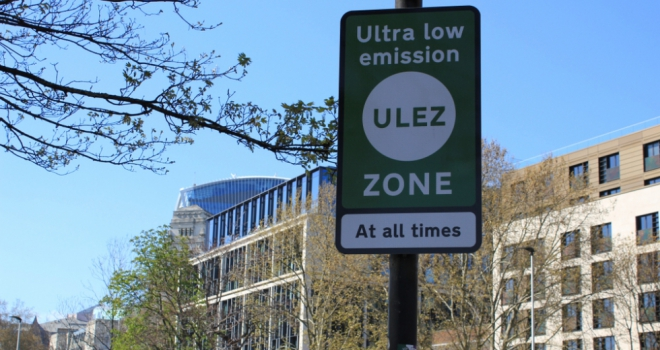
As you know homeowners with older vehicles are facing higher costs. The ULEZ charges £12.50 per day for vehicles that do not meet the emissions standards. This is a significant cost for homeowners who rely on their cars to get around. South London homeowners who live in the ULEZ are facing a loss in property value. According to a recent study, homes in the ULEZ are worth an average of £10,000 less than homes outside the zone. This is because buyers are less likely to want to live in an area where they have to pay extra to drive their cars! Not surprising of course.

Wait for it, combining ULEZ and recent tenant legislation - you can see where it's going, before you know it landlords who rent out properties in the ULEZ will be responsible for paying the ULEZ charge for their tenants' vehicles!

Overall the ULEZ is having a negative impact on South London homeowners. The higher costs, loss in property value, and additional rental costs are making it difficult for homeowners to afford to live in the area.


  • Homeowners are being forced to replace their older vehicles with newer, more expensive models. This is a significant financial burden for many homeowners, especially those on a fixed income.
  • Homeowners are having to find alternative ways to get around, such as public transportation or cycling. This can be time-consuming and inconvenient, especially for those who live in rural areas.
  • Homeowners are feeling less confident about the future of their property values. The ULEZ is one of a number of factors that are making it difficult to predict how property prices in South London will perform in the coming years.

With all these points in mind, where is your next property going to be, inside or outside the ULEZ? Check your property's current value using my online valuation tool or invite me around for a more detailed appraisal!

Monday, 26 June 2023

ULEZ Tax grab sees property prices plummet

Makes sense doesn't it? Taxes go up in a particular area and demand goes down - after all the running cost of living somewhere has just risen for no good. I haven't personally noticed the air quality in Central(ish) London improving, so let's just call it what it is, a tax grab. I have read recently that the ULEZ pilot scheme which covered the Congestion Zone actually did not materially affect house prices.


Shock Horror

Well, I'm not totally surprised. I'm thinking that people within the Congestion Zone are likely to be affluent individuals who more than likely own a newer compliant car anyway, or don't even have a car. So if your income is 7 figures upgrading your car to something slightly newer or whatever is hardly going to break the bank.


What about outer London?

The ULEZ is expanding, as far as zone 6 even. Now here things change dramatically. We haven't got the tube or train infrastructure and people certainly are less well off than those living in penthouses in Belgravia. The impact of having to change their vehicle or pay a daily charge is a greater percentage of their (disposable) income. Let's look at the stats for when it expanded to the South Circular - the impacted boroughs' house prices crept up by 5.3% in the 12 months since October 2021, falling short of the wider London statistic of 5.7%. Westminster actually dropped by 5% - Kensington and Chelsea  as well as Hammersmith and Fulham dropped 4.1% and 1.1% respectively.


Mass Exodus?

It certainly seems like the frog was boiled too vigorously and there is a mass exodus on our hands. Is it ULEZ or are there other factors at play? We can only speculate of course, but looking at it from this angle I'm seeing that the London market could be subdued for some time because of these draconian measures to get everyone in a Tesla. I'm still not convinced, but Sadiq is doing his best to make driving a combustion engine just as expensive! A win for Elon and a win for Sadiq, crafty!


Your property's value

More importantly you are interested in your property's value. To ensure that you future-proof for those that do want to "be green" (get their energy from a coal power plant instead of from a petrol pump) you can install a charging point in your home in order to facilitate such green ambitions. Sadly we are at the mercy of those we vote for, so next time you vote just remember to vote with your house price in mind!


If you are looking for more tips on how to maximise your property's value then do drop me a line and I can help you get the best out of your property. For now why not check out this video I made?


Monday, 1 October 2018

‘Taxing’ Time for the 3,159 Clapham Buy To Let Landlords


Over the last twenty years, there has been a shift in the way the Clapham (and the UK’s) property market works. In the 1960’s, 70’s, 80’s and 90’s, a large majority of twenty somethings saved up their 5% deposit, went without life’s luxuries of going out and holidays etc., for a couple of years and then bought their first home with their hard earned savings.


By 2000, 29.3% of Clapham 25 to 29 years owned their own home (compared to 46% Nationally (and 40.9% of Clapham 30 to 34 year olds in 2000 owned their own home – again compared to 64.2% nationally) whilst the remaining youngsters mostly rented from the Council and in some rare cases, privately rented.


Now it’s 2018, and those levels of homeownership have slipped dramatically and now only 15.6% of Clapham 25 to 29 year olds own their own home and 27.5% of Clapham 30 to 34 year olds own their own home.


There was concern in Government since the late Noughties that this shift from homeownership to private renting wasn’t good for the well-being of the Country and things needed to change, to make it a more level playing field for first time buyers. House prices needed to be more realistic and there needed to be a carrot and stick for both landlords and first time buyers.


In the 1980’s and 1990’s, interest rates were the weapon of choice of Government to cool or heat up the UK housing market – and it did work – up to a point. It’s just interest rates also affected so many other sectors of the UK economy (and not always a in good way). The policy of interest rates to control the economy is called ‘Monetary Policy’. Monetary policy is primarily concerned with the management of interest rates (and the supply of money) and is carried out by the Bank of England (under direction from the Government).


It’s just in this post Credit Crunch, Brexit environment, the use of higher interest rates wouldn’t directly affect landlords (as around two thirds of buy to let properties are bought without a mortgage). Therefore, an increase in interest rates would have hardly any effect on landlords and hit the first time buyers - the people the Government would be trying to help!


Also, given muted growth of real income (i.e. real income being the growth salaries after inflation) in the past few years, an uplift in interest rates (from their ultra-low 0.5% current levels) would have a massive effect on Brit’s household disposable income. Yet, over 90% of new mortgages in 2018 being taken are fixed rate and with such low rates, it has made buying a property comparatively attractive.


Instead, over the last 8 years, the Government has encouraged first time buyers and clipped the wings of landlords with another type of economic policy – Fiscal Policy (Fiscal Policy is the collective term for the taxing (and spending) actions of the Government). First time buyers have had the Help to Buy Scheme, Stamp Duty Exemption and contributions to their deposit by HMRC. On the other side the coin, landlords have had the way they are able to offset the tax relief of their mortgage payments against income change (for the worse), an increase in Stamp Duty (for the worse) and they will be hit with additional costs as the Government will be phasing out fees to tenants in the next 12 to 18 months.


So, what does this all mean for the 3,159 Clapham landlords?


The days of making money in Clapham buy to let with your eyes closed are long gone. There are going to be testing times for Clapham landlords, yet there is still a defined opportunity for those Clapham landlords who are willing to do their homework and take guidance from specialists and experts.


It’s all about looking at your Clapham portfolio (or getting a property professional to do so) and ascertaining if your current portfolio, mortgage and gearing are designed to hit what you want from the investment (because that is what it is – an investment) in terms of income now and income in the future, capital growth and when you plan to dispose of your assets.


I have seen many Clapham landlords (both who use me and my competitors) to manage their rental property or find them tenants – and on many occasions recently, I have told them to SELL – yes sell some of their portfolio to either reduce mortgage debt or buy other types of property that match what they want in the short and long-term from their investments. I know that sounds strange – but my role isn’t just to collect the rent .. it’s also to give strategic advice and opinion on the landlord’s portfolio to help them meet their current and future investment goals.


The opportunities will appear in the Clapham property market for Clapham landlords from gentler growth in property values linked with a restrained Clapham property market, meaning if you put in the time, there will be deals and great bargains to have. Many landlords in Clapham (both clients and non-clients) send me Rightmove links each week, asking my opinion on the suitability of the investment. Some are exceptional – whilst others are duds. The bottom line is, private renting will continue to outgrow first time buyers in the next 5 to 10 years and as we aren’t building enough homes in the UK, which means rents can only go in one direction – upwards!


Do let me know if you are looking to invest and you could use a hand. if you are a ready and able investor sign up to my list that will bring packaged deals to your inbox! If you are looking for no-obligation advice then drop me a line and let's start the conversation.

Friday, 27 January 2017

Lenders are tightening up and here's what it means for investors in South London.


Well it's been another busy month in property investing. Everyone is getting ready to tackle 2017, and by now very well underway to taking action to achieve their goals. If you are looking to invest further in property using good old-fashioned buy to let, be wary though as there are a few things to take note of...

Increased Taxes
I've discussed it before but I'll mention is again - the dreaded Section 24 (of income) tax means that you will be paying the taxman FIRST and then deducting your rental income costs. Brief example:
Old system:
£30,000 Rental profits after repairs
£20,000 Mortgage/loan interest
----------
£10,000 profit so tax bill based on 40% income tax = £4,000

New system:
£30,000 Rental profits after repairs
£30,000 Taxable income, 40% income tax = £12,000

£20,000 Mortgage/loan interest turns into a 20% credit = £4,000

So your tax bill is now £12,000-£4,000 =£8,000!!!! Point to note is that this will be phased in over the next 4 years, so in this example your net income will go down by £1,000 if you do nothing.

That's a whopping increase. Just to put these numbers into perspective it's probably your average owner of two flats in South London receiving a rental of £1800pcm each with a few repairs/improvements thrown in, with loans of about £400,000 on each paying about 3% interest. Could that be you?? Prepare to make less NET profit with your rental portfolio. But you're not alone. In fact, a lot of people did the same as you, kept hold of a flat as they climbed the ladder. Riding the wave of capital appreciation is now resulting in a crash landing. So seek advice and take action. One solution is to incorporate a limited company "newly poor landlord holdings limited" and transfer the flats into that portfolio. Problems arise however when you factor in Capital Gains Tax and Stamp duty, so it's likely that those costs will outweigh any savings for a long, long time (although you may be able to claim reliefs to put off the tax though). Plus of course that you need to pay 20% corporation tax on the profits and further taxes when you take the money out of the limited company. All food for thought and there is no "one-size-fits-all" solution. Seek professional advice.

Rental Stress Tests
Banks have, over the last month tightened up a little bit on lending. Whereas in the distant past a rental coverage of 125% of the interest payment would suffice (i.e. the rent was 125% of the mortgage payment), they changed it to 125% at a stress rate of 5% but now they have gone as far as to ask for 145% cover at 5% and sometimes even 5.5%. Why? Linked to the point above it's simply because taxes are on the increase and mainstream buy to let lenders are covering themselves, adding in several more layers of protection to make sure that payments are met.


So what's next for landlords in Clapham?
I remain unconvinced that incorporating and transferring the existing portfolio will be the best solution. If you are in Liverpool, Leeds, Sunderland, the outer Hebrides where property prices perhaps have not moved very much then CGT will be minimal, as will SDLT, Incorporating is the right thing because your rental income will be taxed at 20% (Corporation Tax) instead of 40-45% (depending on your income tax bracket). I will take a wild guess and assume that if you're reading this you will be in a good, stable job, enjoy what you are doing and are simply investing on the side. Very wise of course. But if you are looking to invest further I would certainly do it in a limited company going forward. It's a very straightforward process and shouldn't take more time than thinking of a name for a limited company and a few pounds to register it at Companies House. You can, of course, file your accounts and so forth yourself but if you are going through the trouble of reducing your taxes you will want to ensure you get the most benefits you can. I have a brilliant accountant of course, and she ensures I get all the tax breaks I can. If you'd like her details just drop me an email and I'll introduce you, no problem. Going forward I'd highly recommend seeking out a whole of market broker to enable you to get hold of some of the best deals from lenders that don't deal with the general public such as Kent Reliance, Precise and Paragon.

If you are a landlord and/or investor looking to maximise your portfolio profits then get in touch. I offer a range of things from portfolio reviews to site visits to give practical advice tailored to your property. Start the conversation by email.
Image result for i would love to hear from you

Links for further reading on the matter:

One in three landlords now want a guarantor: how tenants in Clapham, Brixton and Streatham can still land a flat

Not a day goes by that we don't hear about tenants being squeezed. This week's twist: it's not just the rent, it's who you k...

Popular Post!